Industrial and construction-services consolidation is not running out of fuel. EMCOR Group’s agreement to acquire P1 Construction, LLC, announced on November 13, 2026, places another strategic marker in a market where infrastructure spending and data-center construction are reshaping the competitive landscape.
For shareholders of EMCOR, listed on the NYSE under $EME, the message is straightforward: scale and specialized capabilities remain valuable when customers are committing capital to complex mechanical and electrical projects. The deal does not disclose a purchase price, financing terms, closing date or expected earnings impact, but its strategic direction is clear.
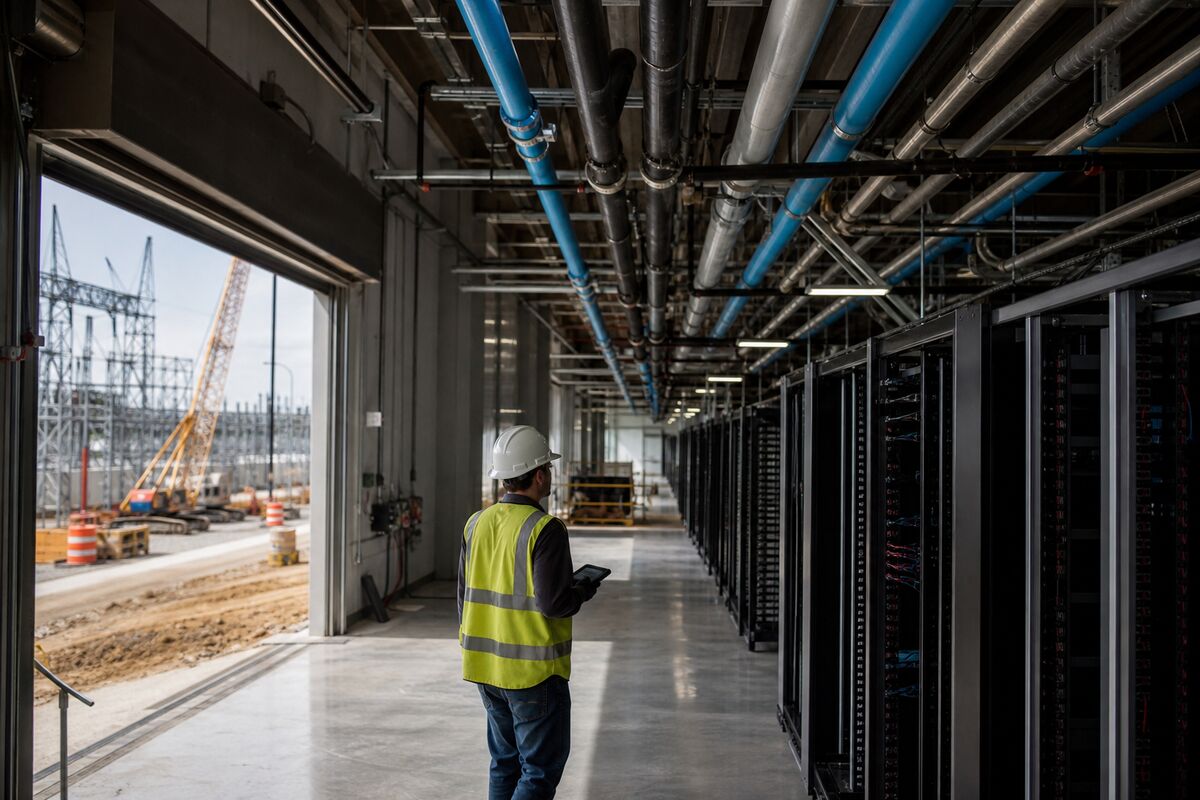
According to the November 13 BusinessWire release, EMCOR announced a definitive agreement to acquire P1 Construction, LLC. P1 is described as a mechanical and electrical contractor serving high-growth markets. Those capabilities sit close to the spending priorities currently influencing the broader industrial economy: infrastructure investment, advanced facilities and data-center buildouts.
A strategic fit, not a disclosed forecast
The distinction matters. The announcement establishes the transaction and P1’s market positioning. It does not, based on the supplied information, quantify backlog, revenue contribution, margins, synergies or the timing of completion. Any claim about near-term earnings would therefore be speculation rather than analysis.
What can be said is that mechanical and electrical work is central to the construction and operation of sophisticated facilities. Contractors with exposure to high-growth markets may offer strategic value to larger platforms seeking broader capabilities and customer access. EMCOR’s proposed acquisition of P1 consequently fits a familiar consolidation logic: combine scale with specialized execution in areas where project complexity and capital requirements are elevated.
Why consolidation is gaining attention
Industrial and construction-services companies are operating against a sector backdrop shaped by elevated infrastructure spending and demand for data-center construction. Those trends may encourage larger contractors to expand through acquisition rather than rely solely on organic growth. Acquiring an established contractor can potentially add expertise, workforce capacity and relationships in markets where demand is developing quickly.
Still, the sector context should not be confused with deal-specific disclosure. The supplied announcement does not state that P1 has a particular data-center contract, nor does it quantify the company’s exposure to infrastructure projects. The more disciplined conclusion is narrower: P1 serves high-growth markets, while broader infrastructure and data-center demand may help explain why specialized contractors remain strategically relevant.
The investor lens
For investors analyzing $EME, the transaction is best viewed as a signal about capital allocation and industry structure rather than as a fully modeled financial event. The absence of a disclosed purchase price, financing terms, closing date and expected earnings impact leaves important questions unanswered.
The larger takeaway is that consolidation may continue where technical expertise intersects with durable construction demand. EMCOR’s P1 agreement suggests that leading service platforms are still looking for ways to deepen their presence in specialized, high-growth markets. Whether that translates into measurable financial benefits will depend on terms and execution that have not been provided.
Bull/Bear Verdict
Bull Case: EMCOR’s agreement to acquire P1 Construction could strengthen exposure to high-growth mechanical and electrical contracting markets as infrastructure spending and data-center buildout demand remain important sector themes.
Bear Case: The announcement provides no purchase price, financing terms, closing date or expected earnings impact, leaving the transaction’s financial effect and execution outcome uncertain.