U.S. midstream consolidation is not slowing down—and Energy Transfer’s $2.62 billion acquisition of Vaquero Midstream is the latest evidence. The cash-and-stock transaction places pipeline and gathering infrastructure squarely back in the spotlight for energy-focused investors tracking asset valuations, transaction structures and the next wave of sector M&A.
This is more than a single corporate deal. Energy Transfer’s agreement to acquire Vaquero Midstream adds to the consolidation of U.S. energy infrastructure at a time when strong domestic oil and gas production continues to reinforce the importance of gathering and pipeline assets. The transaction’s scale also offers a useful reference point for how the market may assess midstream businesses.
According to the Seeking Alpha merger report, Energy Transfer agreed to acquire Vaquero Midstream in a $2.62 billion cash-and-stock deal. The announcement provides limited transaction detail, but the headline figure alone makes the agreement relevant to investors evaluating the direction of U.S. midstream valuations.
Why the deal matters for midstream assets
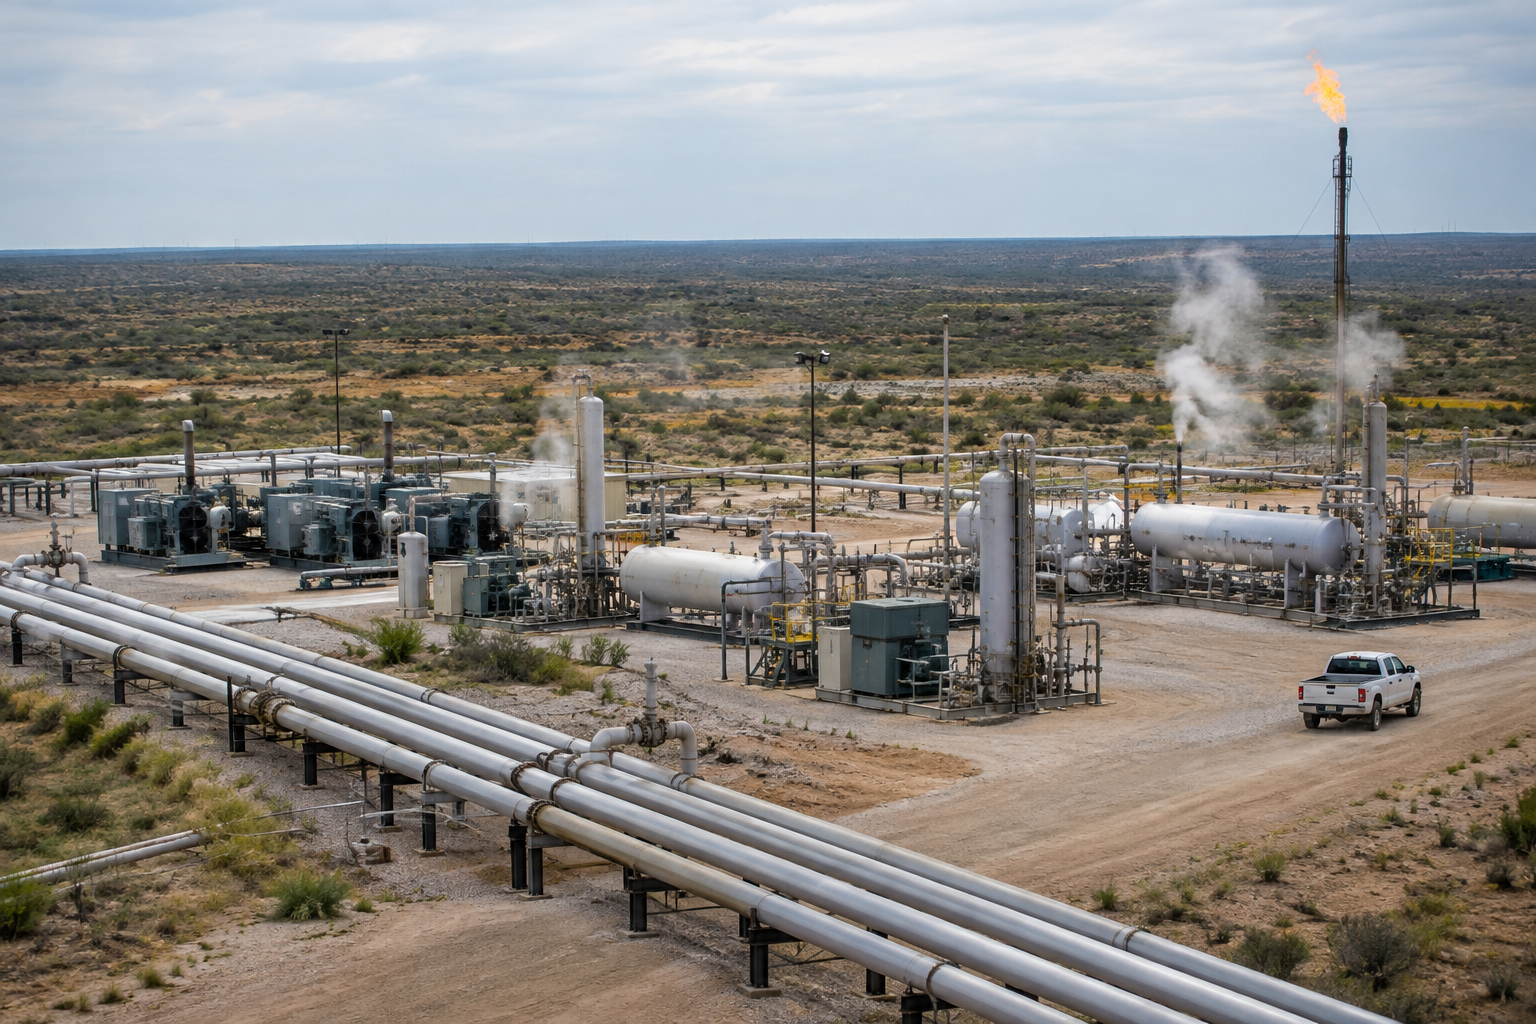
Pipeline and gathering systems are strategically important pieces of the domestic oil and gas network. Gathering assets connect production to broader transportation infrastructure, while pipelines provide the movement capacity needed across the energy system. In a market characterized by strong domestic oil and gas production, control of those assets can carry strategic significance.
That strategic relevance helps explain why consolidation remains a central theme in the midstream sector. Acquirers may seek to expand infrastructure positions, while sellers may find a receptive market for established pipeline and gathering businesses. The Vaquero transaction therefore fits a broader industry pattern: established infrastructure is becoming an increasingly important focus of energy-sector M&A.
Cash and stock change the investor calculation
The structure of the deal matters as much as its $2.62 billion value. A cash-and-stock transaction requires investors to look beyond the announced headline consideration and examine how value is being delivered. Cash provides one component of consideration, while stock links part of the transaction’s value to the acquiring company’s equity.
That distinction is important when assessing potential dilution. Because the assignment does not provide the cash-and-stock split or the number of shares involved, investors cannot determine the precise equity impact from the announced value alone. Still, the structure highlights a key issue in acquisition analysis: headline transaction value and the eventual effect on ownership are related, but they are not identical questions.
A reference point for sector M&A
For energy-focused investors, the Vaquero deal may serve as another data point in evaluating midstream valuations and potential M&A premiums. The announcement does not disclose a premium, financial projections or additional deal terms, so no conclusion can be drawn about whether Vaquero was acquired at a particular valuation or premium.
What can be said is more direct: Energy Transfer’s agreement to acquire Vaquero Midstream for $2.62 billion reinforces consolidation as a defining feature of U.S. midstream infrastructure. The combination of a sizable transaction and a cash-and-stock structure gives investors two areas to monitor—how pipeline and gathering assets are valued, and how acquirers balance transaction funding with potential equity dilution.
That is the practical takeaway. The deal does not provide a complete valuation template for the sector, but it does establish a clearly identified transaction against which future midstream M&A activity may be compared.
Bull/Bear Verdict
Bull Case: The $2.62 billion Vaquero Midstream acquisition may support the view that pipeline and gathering assets remain strategically valuable, reinforcing continued U.S. midstream consolidation and future M&A relevance.
Bear Case: The cash-and-stock structure could introduce potential dilution, while the lack of disclosed transaction terms, premiums and financial projections limits what investors can conclude about valuation from the $2.62 billion headline alone.