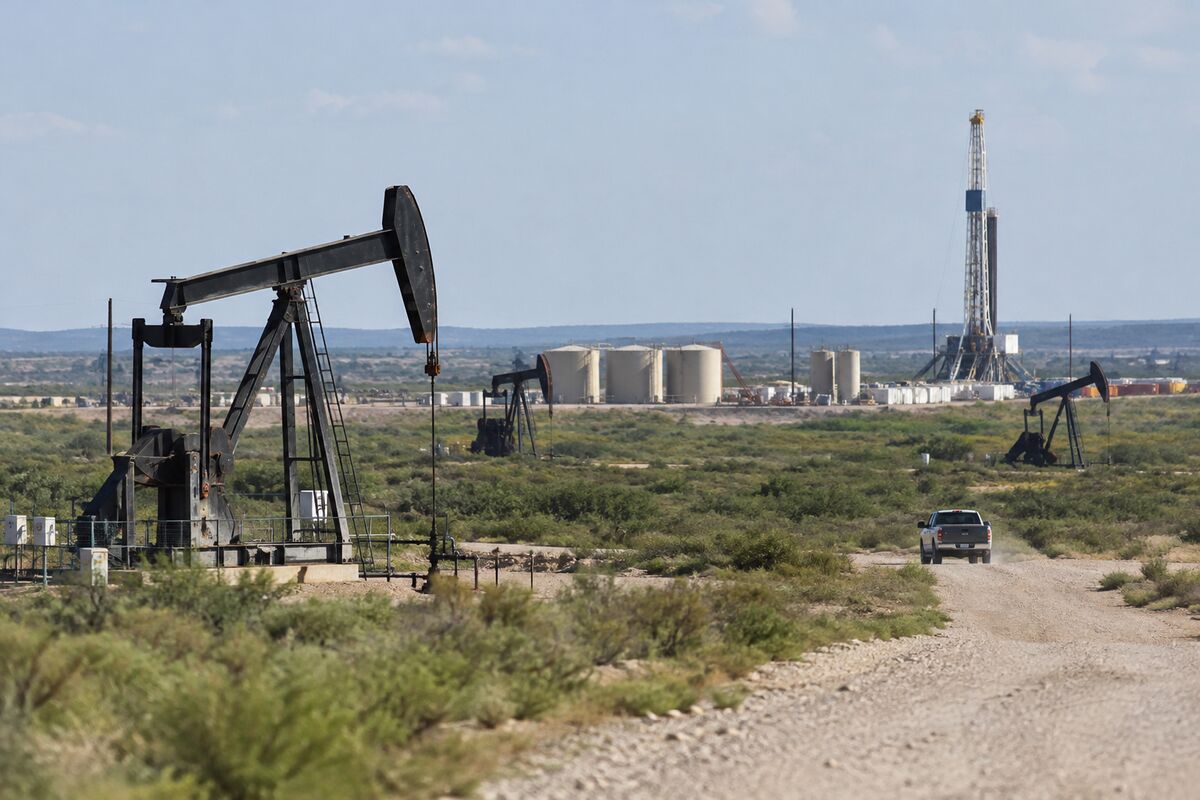
U.S. shale gas is entering an era where scale may matter more than acreage alone. EQT Corporation’s agreement to acquire Range Resources in a $50 billion all-stock transaction would create the largest natural gas producer in the United States—a move that puts consolidation, capital structure and geopolitical exposure at the center of the energy debate.
This is not simply a corporate combination. It is a statement about how America’s gas industry may be positioning itself for a market shaped by volatile commodity prices, geopolitical tensions and the increasing importance of operating scale. For shareholders tracking $EQT and $RRC, the transaction provides a direct test of whether size can translate into strategic leverage without erasing the discipline that shale investors have demanded.
A landmark transaction for U.S. gas
EQT has agreed to acquire Range Resources through an all-stock deal valued at $50 billion. If completed, the combination would create the largest U.S. natural gas producer. That designation matters because production scale can influence how a company approaches infrastructure, drilling priorities and exposure to regional gas-market conditions.
The transaction also gives the industry a clear signal: consolidation is no longer a side theme in U.S. shale. It may be becoming a central strategy. The shale sector was built on thousands of individual drilling decisions and intense competition for acreage, but a more mature market can reward companies that combine assets, operations and financial resources under one corporate structure.
The announced deal does not, by itself, establish what the combined company’s future production profile or valuation metrics will look like. Those details are not provided in the announcement. What is clear is the strategic ambition: EQT is pursuing a transaction large enough to reshape the competitive map of U.S. natural gas.
Why the all-stock structure matters
An all-stock transaction links the economics of the deal to the equity values of the two companies rather than presenting it as a cash purchase. That structure can make the post-transaction relationship between EQT and Range Resources shareholders especially important. Existing holders of both companies would have an interest in how the combined enterprise is positioned and how the market evaluates its prospects.
For EQT, the structure may also limit the need to frame the transaction around an immediate cash outlay. For Range Resources shareholders, it means the deal’s implications extend beyond the headline $50 billion figure: their exposure would be tied to the future performance and market perception of the enlarged EQT-led company.
That is the essential investor question. A larger producer is not automatically a more valuable producer. The market may focus on whether consolidation improves strategic flexibility and operating coherence, rather than simply celebrating the size of the combined resource base.
Geopolitical pricing risk moves into focus
The announcement arrives amid elevated oil and gas prices associated with tensions in the Middle East. That backdrop gives the transaction immediate relevance, but it also complicates the interpretation. Higher prices can strengthen the appeal of domestic production and increase the strategic importance of U.S. gas. At the same time, geopolitical pricing shocks can create a more volatile operating environment.
For a company positioned as the largest U.S. natural gas producer, that exposure may become more visible. The combined entity could have greater importance in discussions about domestic supply, market resilience and the United States’ role in global energy markets. Yet larger scale may also make the company a more prominent proxy for expectations about gas prices and geopolitical risk.
That is where the deal becomes more than a shale consolidation story. It may represent a wager that scale provides a stronger platform for navigating a market in which energy prices are increasingly influenced by events beyond North American production fields.
The bottom line for $EQT and $RRC
Investors tracking $EQT and $RRC now have a transaction that could redefine the competitive structure of U.S. natural gas. The agreement is significant because it combines a $50 billion all-stock consideration with a clear strategic outcome: the creation of the largest U.S. gas producer if completed.
Still, the market will likely distinguish between headline scale and delivered value. The transaction’s importance lies in what it says about the next phase of shale: fewer, larger producers; more emphasis on consolidation; and greater sensitivity to geopolitical pricing conditions. The source announcement is available from Seeking Alpha.
Bull/Bear Verdict
Bull Case: The $50 billion all-stock combination could give EQT and Range Resources greater scale and create the largest U.S. natural gas producer, potentially strengthening its strategic position as geopolitical tensions keep energy prices elevated.
Bear Case: The all-stock structure leaves shareholders exposed to the future market performance of the combined company, while the larger producer could also face greater sensitivity to volatile gas prices and Middle East-related geopolitical risk.