Fuel remains the airline industry's most unforgiving co-pilot: always aboard, never flexible, and capable of reshaping an earnings report before passengers even take their seats. JetBlue's wider quarterly loss puts that exposure back in the spotlight, showing how quickly fuel costs can squeeze an airline's margins.
For $JBLU, the more important question is whether management's recovery plan can create enough financial lift to offset continued cost pressure. The airline's chief executive said margins are improving, while pointing to cost reductions and higher premium revenue as key parts of the effort. That is an encouraging direction—but fuel remains a powerful variable outside the cockpit.
Fuel costs turn operating plans into moving targets
JetBlue's result offers a straightforward lesson for transportation and energy-sensitive investors: airline margins are closely tied to the cost of fuel. When fuel expenses rise, an airline may have limited ability to immediately pass the increase through to customers without affecting demand or its competitive position. The result can be pressure on the difference between what the airline earns and what it spends to operate.
That sensitivity makes oil-market conditions more than a background economic theme for carriers. Changes in energy markets can filter into airline performance through fuel costs, adding uncertainty to planning and making margin recovery harder to sustain. JetBlue's wider quarterly loss, which the company tied to fuel costs, is therefore not merely an isolated accounting headline. It is a reminder that an airline's financial trajectory can be pulled off course by an input it does not control.
The reported results and management commentary are covered in CNBC's report on JetBlue's quarterly earnings.
The recovery plan has two levers
JetBlue's response rests on two broad levers: reducing costs and generating more revenue from premium offerings. Cost-cutting can help the carrier improve margins by lowering expenses that management can influence. It may also provide some cushion when fuel costs remain demanding, although the assignment does not provide enough detail to measure the scale or timing of those savings.
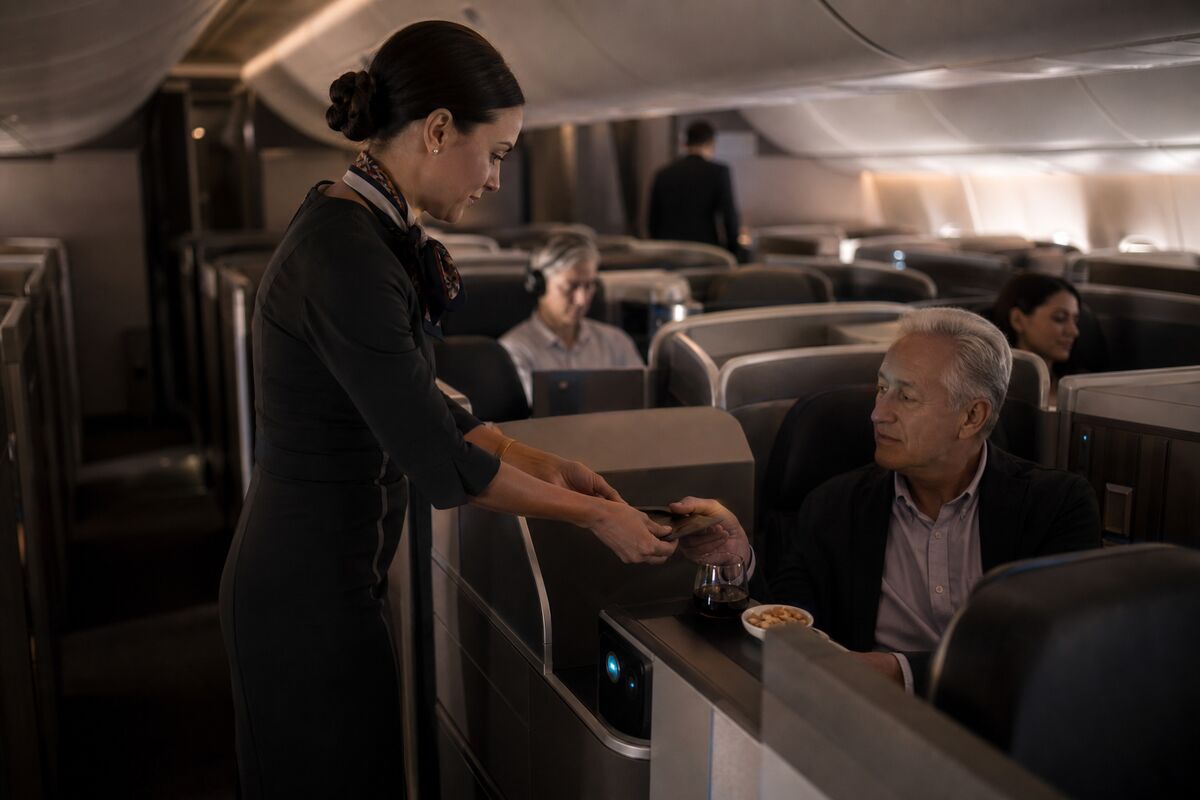
The premium-revenue initiative approaches the challenge from the other side of the ledger. Rather than relying only on lower expenses, JetBlue is seeking higher-value revenue from customers willing to pay for a more premium experience. If successful, that strategy could improve the economics of each flight and give the airline another way to absorb cost pressure.
Still, the plan is not a magic shield against energy-market swings. Cost reductions may take time to show up fully, while premium revenue depends on customer demand and the airline's ability to execute. Management's statement that margins are improving provides a constructive signal, but it does not erase the drag from fuel costs that contributed to the wider quarterly loss.
Why the margin story matters
The tension between improving margins and higher fuel-related pressure is the central story in JetBlue's results. Management is attempting to build a more resilient business through actions within its control, while energy costs remain exposed to forces beyond the airline's direct reach.
That makes the next phase of the story less about a single quarterly result and more about durability. Can cost reductions and premium revenue continue to support margins if fuel pressure persists? The available information does not answer that question. It does, however, clarify the test facing $JBLU: management must demonstrate that its internal improvements can keep pace with an external cost burden capable of changing the economics of air travel.
Bull/Bear Verdict
Bull Case: JetBlue's CEO says margins are improving, and cost reductions combined with higher premium revenue could help offset the fuel costs tied to the airline's wider quarterly loss.
Bear Case: Fuel costs contributed to the wider quarterly loss, and continued energy-market pressure could limit the benefit of cost-cutting and premium-revenue initiatives.