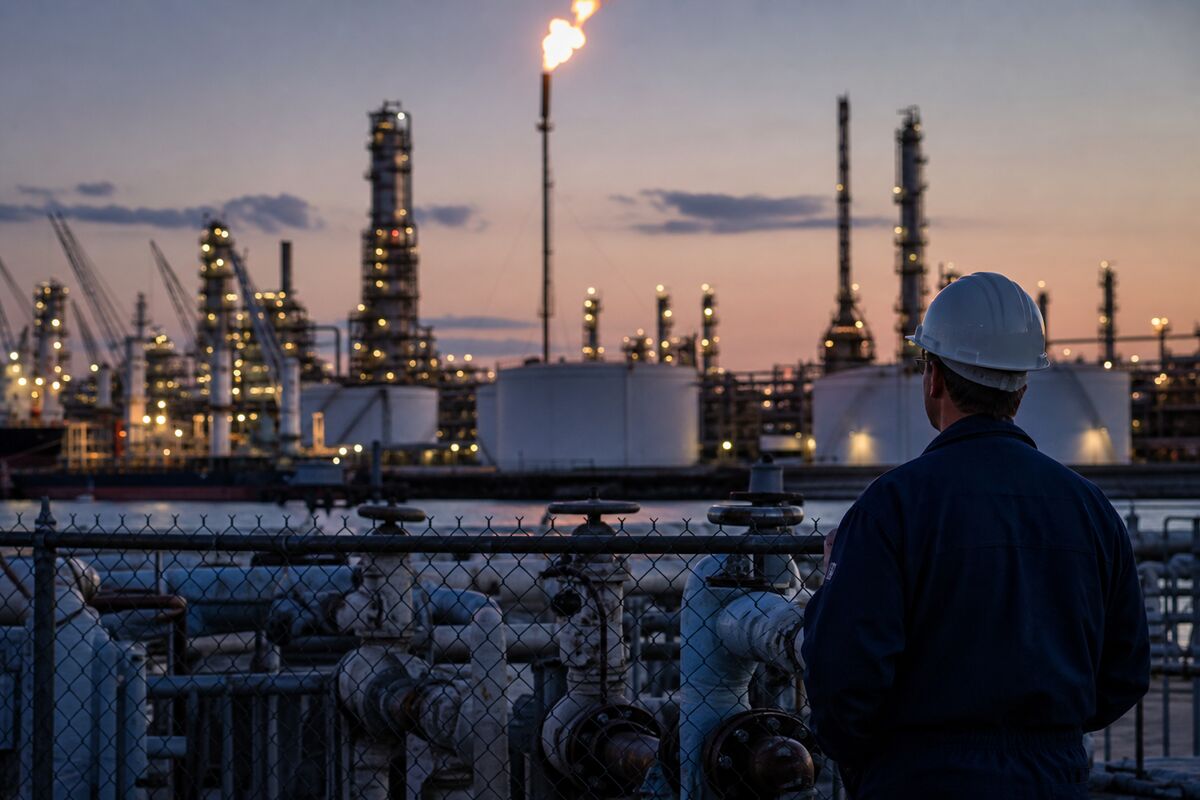
Marathon Petroleum has put two powerful signals on the energy-trading screen: refining margins surged enough to help the company beat profit estimates, while a $4.2 billion refinery deal with CVR Energy points to another round of consolidation in the US downstream sector.
That combination matters because it ties a strong operating quarter to a strategic bet on scale—just as oil markets are being buffeted by uncertainty around the Iran war and the US midterm election outcome. The headline is not simply that one refiner delivered an earnings beat. It is that refining strength and industry consolidation are arriving together, creating a sharper test of how durable the downstream advantage may be.
Marathon Petroleum’s results offer the immediate catalyst. The company benefited from soaring refining margins, according to the announcement, giving traders a direct read on the economics of turning crude into refined products. In a market where crude prices and geopolitical headlines can move rapidly, that distinction is important: strong refining margins are a downstream signal, while broader crude-market exposure is a separate question.
In other words, the earnings beat does not automatically settle the larger oil-market debate. Refining margins may strengthen even as the crude backdrop remains unsettled, and the source does not provide enough information to establish how the two forces will interact from here. For traders, that separation is central. A refiner’s performance can reflect the value captured in processing, while crude-related volatility may create a different set of pressures and opportunities across the energy complex.
A $4.2 Billion Vote on Scale
The proposed refinery transaction with CVR Energy gives the earnings story a strategic second act. At $4.2 billion, the deal is large enough to frame consolidation as more than a footnote to Marathon Petroleum’s quarterly performance. It suggests that asset ownership and operating scale remain prominent considerations for US downstream companies, particularly when margins are strong.
But the deal also shifts attention from announcement to execution. Investors and traders will be watching the transaction’s progress, the practical combination of the businesses and whether the expected strategic logic survives the process. The announcement establishes the size of the bet; it does not, by itself, answer how effectively the assets will be integrated or how the combined operation may perform through a different margin environment.
The market’s real question is whether Marathon Petroleum is buying into durable downstream strength—or committing significant capital while that strength is elevated.
Volatility Raises the Stakes
The timing adds another layer of uncertainty. Oil-market volatility linked to the Iran war and the outcome of the US midterm election has created a backdrop in which geopolitical and political developments can quickly reshape market expectations. That does not erase the significance of the refining-margin beat, but it makes the durability question harder to ignore.
For the US downstream sector, the announcement points toward a contest between current margin strength and future uncertainty. Consolidation could matter if scale helps companies navigate volatile conditions, but the source provides no basis for assuming that elevated refining margins will persist. Traders therefore face a familiar but consequential checklist: Can the CVR Energy deal be executed as announced? What does the combination mean for competitive dynamics? And are today’s soaring margins a durable feature of the market or a powerful but temporary signal?
Marathon Petroleum’s announcement answers one question clearly: refining economics are strong enough to support an earnings beat and a $4.2 billion strategic move. The harder questions—about crude exposure, geopolitical volatility and the lifespan of those margins—remain open. That uncertainty is precisely what makes the transaction a market story rather than merely a corporate one. Read the source report for the announcement details.
Bull/Bear Verdict
Bull Case: The earnings beat, soaring refining margins and $4.2 billion CVR Energy refinery deal could indicate that scale and downstream strength are becoming more important in a volatile US oil market.
Bear Case: The deal’s $4.2 billion price tag raises execution questions, while the available information does not establish whether the soaring refining margins can persist amid Iran-war and US midterm-election uncertainty.