Oil and gold are telling two very different stories. WTI Crude and Brent Crude weakened after comments from Trump about talks with Iran reduced fears of a supply disruption, while gold climbed more than 1% as the US dollar softened and investors continued to seek a safe-haven asset.
That split is more than a daily market curiosity. It is a snapshot of how quickly traders can rotate between competing macro narratives: geopolitical de-escalation can drain the risk premium from crude, even as a weaker dollar and lingering uncertainty keep gold in demand. For US and Canadian resource investors, the divergence puts energy and precious metals on opposite sides of the same positioning question.
Iran removes some heat from crude
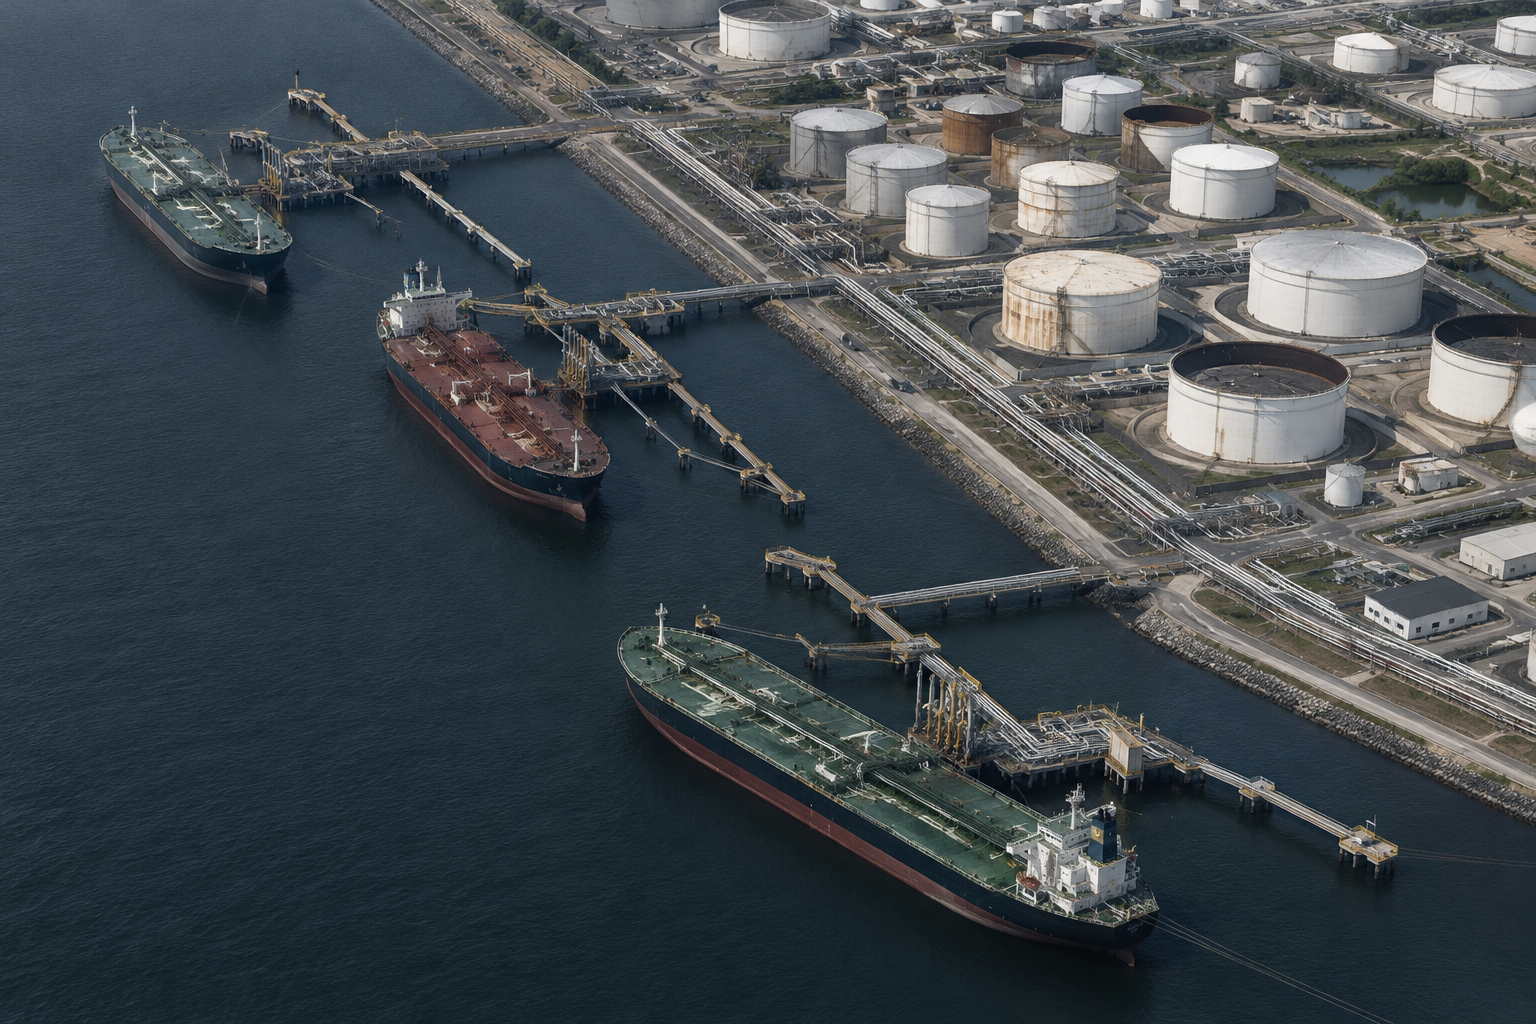
Oil prices often carry a geopolitical surcharge. When traders fear that conflict could interrupt production, shipping or exports, crude can reflect not only current supply and demand, but also the possibility of a tighter market ahead. Comments about Iran talks appear to have reduced that perceived disruption risk, leaving WTI Crude and Brent Crude under pressure.
The mechanism is straightforward: if the probability of a supply shock appears to decline, some of the urgency embedded in crude pricing may fade. That does not require a sudden change in physical oil consumption. It can happen simply because traders reassess the range of outcomes and remove part of the geopolitical premium.
China’s planned resumption of October fuel exports adds another supply-side consideration. According to four trade sources, China is set to restart those exports after a brief halt. The development could reinforce the idea that product availability may be less constrained than recently feared, giving energy traders another reason to watch the supply outlook rather than focus solely on geopolitical headlines.
Gold catches the softer-dollar bid
Gold moved in the opposite direction, gaining more than 1% as oil prices eased and the US dollar weakened. Because gold is priced in dollars, a softer US currency can make the metal relatively more attractive to holders of other currencies. At the same time, safe-haven demand can support gold when investors remain alert to political and economic uncertainty—even if one immediate supply concern is cooling.
That is the key cross-asset distinction. Crude is responding to the prospect of fewer supply disruptions; gold is responding to currency conditions and the broader desire for protection. One market is shedding a geopolitical premium, while the other is retaining a defensive bid.
Energy equities are not following crude lower
The sector picture adds another layer. Yahoo Finance data reported gains of 2.72% for Oil & Gas Integrated, 3.03% for Refining & Marketing, and 2.05% for E&P. Those moves show that a weaker crude benchmark does not automatically translate into weakness across every energy grouping.
Refiners, in particular, can be influenced by factors beyond the headline oil price, while integrated and exploration-and-production businesses may respond to broader sector flows and expectations. The reported gains therefore complicate any simple “oil down, energy stocks down” interpretation.
For US and Canadian resource investors, the takeaway is a market divided by exposure. Energy may be navigating softer geopolitical pricing and changing fuel-export expectations, while precious metals may be benefiting from the weaker dollar and safe-haven demand. That creates the possibility of sector rotation, but it also underscores the need to distinguish between commodity moves and equity performance.
Crude’s decline does not erase the importance of supply risks, and gold’s rally does not guarantee that defensive demand will persist. The more useful signal may be the divergence itself: traders are reducing one kind of risk premium while maintaining another.
For additional sector data, see Yahoo Finance’s energy-sector overview.
Bull/Bear Verdict
Bull Case: Gold may retain support if the softer US dollar and safe-haven demand continue, while reported gains of 2.72% in Oil & Gas Integrated, 3.03% in Refining & Marketing, and 2.05% in E&P suggest energy equities could remain resilient despite weaker crude.
Bear Case: Further easing of Iran supply concerns and China’s planned resumption of October fuel exports could keep pressure on WTI Crude and Brent Crude, while the more than 1% gold gain may fade if dollar and defensive-demand support weakens.