Oil markets are being pulled in opposite directions: the IEA says the world market is returning to surplus as Gulf exports recover, while tensions surrounding the Iran blockade, the Strait of Hormuz and attacks on tankers keep a geopolitical fuse burning beneath crude.
That clash is already showing up in the tape. Oil prices are headed for a second consecutive weekly decline even as Trump maintains the Iran blockade, and US commercial crude inventories rose by 4.7 million barrels to 414.4 million barrels in the week ending November 6. For traders watching WTI and Brent, the message is less a clean signal than a market caught between barrels returning to circulation and the possibility of disruption.
The IEA’s surplus warning gives the supply side of the story a clear headline. As Gulf exports recover, more crude may become available to a market that is simultaneously receiving a tangible inventory signal from the United States. The EIA data do not settle the broader global balance on their own, but the increase in commercial crude stocks adds weight to the argument that supply may be outpacing near-term demand in at least part of the system.
That matters because crude pricing is often a contest between what is visible in storage data and what traders fear could happen next. Recovering Gulf exports are visible. So is the 4.7-million-barrel rise in US commercial inventories. The potential consequences of tensions around the Strait of Hormuz and attacks on tankers are more difficult to measure, but they can still influence how market participants value the barrels expected to arrive later.
Reporting supplied for this analysis describes the geopolitical backdrop as a continuing source of uncertainty, with Trump maintaining the Iran blockade and tensions involving the Strait of Hormuz and tanker attacks adding to concern about energy flows. Those claims should be treated as reported developments rather than as a standalone forecast for crude. Their market significance lies in the possibility that a disruption could complicate the surplus narrative, even while current information points toward heavier supply.
The result is a push-pull market for both WTI and Brent. The IEA’s warning and the rise in US inventories may encourage traders to focus on surplus conditions and the prospect of recovering Gulf exports. The reported geopolitical tensions may pull attention back toward supply security and transport routes. With oil prices already headed for a second weekly decline, the balance of those forces currently appears to be weighing on crude, though the geopolitical risks make a straight-line interpretation difficult.
What the inventory number changes
The EIA’s 414.4 million-barrel figure gives the US market a concrete reference point as year-end trading approaches. A 4.7-million-barrel weekly increase suggests that commercial storage is not currently reinforcing a scarcity narrative. For WTI-linked trading, that may keep inventory trends in focus, particularly as participants compare domestic stock movements with the broader IEA view of a returning global surplus.
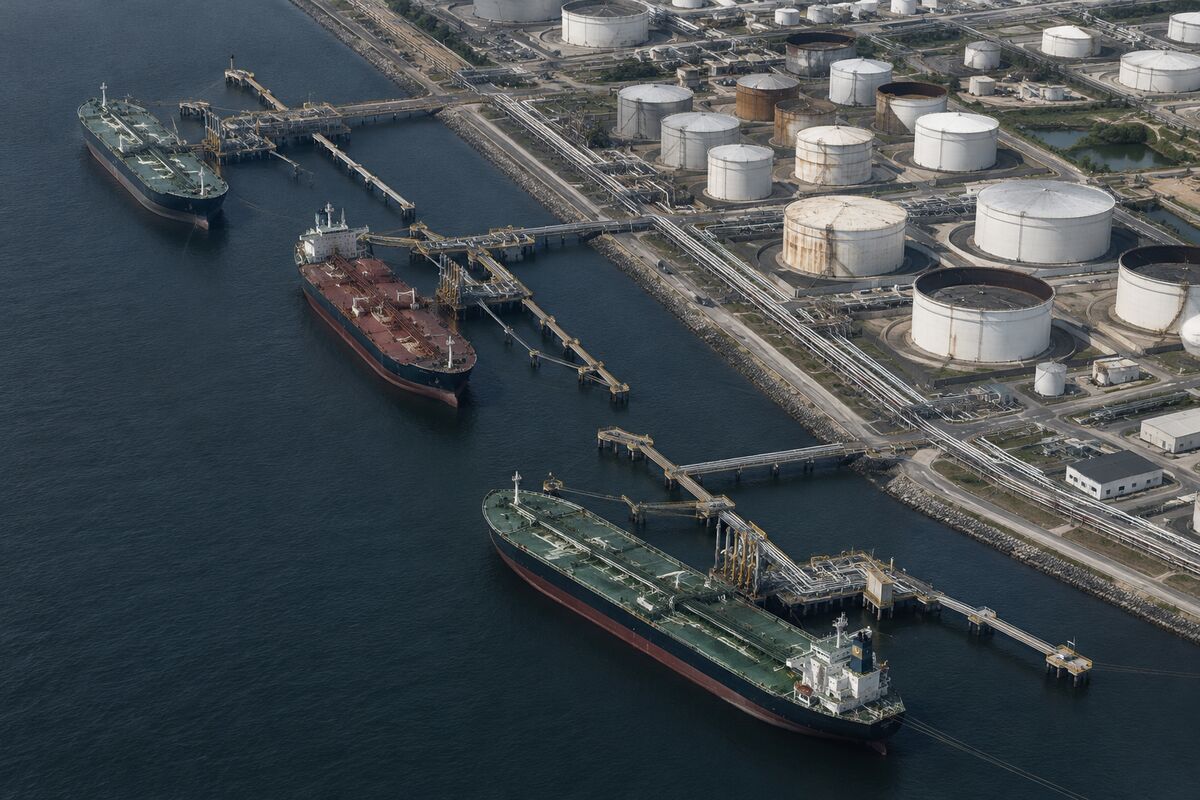
For Brent, the Gulf-export recovery and the reported Strait of Hormuz tensions create a similarly divided setup. Brent reflects the wider seaborne crude market, making export flows and tanker-related developments especially relevant to how traders interpret the supply outlook. The same event can therefore carry two opposing readings: recovering exports may signal improved availability, while attacks on tankers may raise concern about the reliability of those flows.
What it could mean for energy equities
US and Canadian energy equities and crude-linked stocks may inherit that uncertainty heading into year-end trading. Companies with greater sensitivity to WTI or Brent may see market attention shift between the inventory build, the IEA’s surplus warning and the geopolitical headlines. A softer crude backdrop could weigh on sentiment toward the sector, while renewed concern about Gulf shipments or tanker security could provide a counterforce through the pricing of supply risk.
That does not produce a single read-through for every US or Canadian energy stock. The assignment does not identify individual equities, and the available data do not support company-specific conclusions. The more defensible takeaway is that crude exposure may remain headline-sensitive: inventory and export data point toward surplus pressure, while Iran-blockade tensions and tanker attacks could keep abrupt changes in market expectations in play.
For traders, the year-end question is whether physical supply evidence continues to dominate the narrative. The IEA’s surplus warning, recovering Gulf exports and the EIA’s 4.7-million-barrel inventory increase all point in one direction. The geopolitical developments attributed to the supplied reporting point in another. Until those forces resolve, WTI and Brent may remain markets where the next headline matters almost as much as the last barrel.
Read the supplied oil-market reporting at OilPrice.com.
Bull/Bear Verdict
Bull Case: Tensions involving the Strait of Hormuz and reported tanker attacks could support WTI and Brent if traders place greater weight on supply-disruption risk than on recovering Gulf exports.
Bear Case: The IEA’s surplus warning, recovering Gulf exports and the EIA-reported 4.7-million-barrel rise to 414.4 million barrels may continue to pressure crude sentiment and crude-linked US and Canadian energy equities.