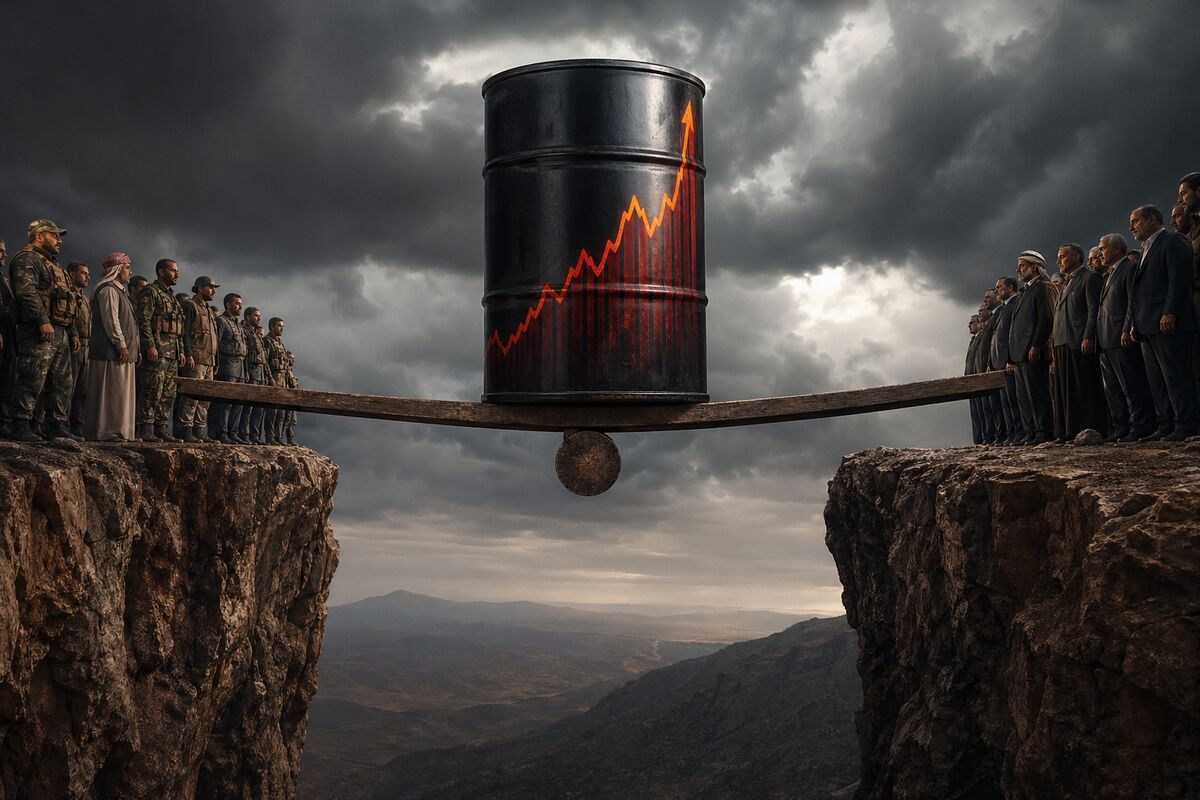
Oil’s rally is not a clean bullish signal for equities. Brent crude reached a five-month high after attacks on ships and Saudi energy and airport sites claimed by the Houthis, putting Canadian producers in the spotlight while raising a more uncomfortable question for investors: how much of the energy benefit survives if inflation and geopolitical risk spread across the broader market?
That tension is now the central trade. Higher crude prices may improve the revenue backdrop for producers such as Canadian Natural Resources Limited, listed as $CNQ.TO, and ConocoPhillips, listed as $COP. But the same shock could pressure US and Canadian equities through higher energy costs, a more difficult inflation outlook and deteriorating risk sentiment. The market is rewarding scarcity while discounting instability.
Reuters reporting cited in the market coverage places the crude move alongside a sharp deterioration in regional sentiment. Most Gulf bourses retreated following the attacks, an immediate reminder that an oil shock can benefit producers while simultaneously damaging confidence in risk assets.
Producers get the clearest first-order benefit
For an upstream company, the logic is direct: when crude prices rise, each barrel sold may generate more revenue before operating costs and other expenses. That is the mechanism putting $CNQ.TO and $COP on the trader’s radar. If the price increase persists, higher cash inflows could give producers more flexibility around spending, balance-sheet decisions and shareholder distributions.
But a headline oil spike is not the same as a durable change in the commodity cycle. The attacks have introduced a geopolitical premium, and that premium may fade, expand or remain volatile depending on the next developments. For producers, the key issue is therefore not simply whether Brent touched a five-month high. It is whether the disruption produces sustained pricing power without creating an economic slowdown that eventually weakens demand.
TC Energy presents a different question
TC Energy Corporation, listed as $TRP.TO, belongs in the conversation, but not for the same reason. As a pipeline operator, it is exposed to the importance of energy infrastructure and transportation networks. However, the assignment does not establish a direct earnings impact from the Brent move, and none should be assumed.
That distinction matters. A higher oil price may improve sentiment toward the energy complex and increase attention on infrastructure operators, but it does not automatically translate into a matching change in pipeline earnings. For $TRP.TO, the immediate market implication may be more about sector positioning, risk appetite and the perceived strategic value of energy infrastructure than a mechanically higher profit forecast.
The inflation problem is moving back to center stage
The geopolitical backdrop is particularly sensitive because US Strategic Petroleum Reserve oil stocks have fallen to their lowest level since 1982, according to Reuters reporting. That reduces the market’s sense of available cushion at precisely the moment supply security is becoming more important.
Higher oil prices can filter through transportation, industrial and consumer costs. For US and Canadian markets, that may complicate the inflation outlook and keep pressure on rate-sensitive areas of equities. The result is a narrow leadership pattern: energy producers may benefit from the commodity move, while the broader market could face a more difficult combination of higher input costs and weaker risk sentiment.
Oil majors face a spending test
The next test is capital allocation. Iran-war-related windfall cash raises questions about whether oil majors will direct additional funds toward production, return capital to shareholders or preserve financial flexibility. Higher prices create room to spend, but history offers a warning: commodity booms can encourage expansion just as the market begins questioning their durability.
That makes discipline more important than celebration. A temporary geopolitical premium may produce cash, but deploying that cash as though elevated prices are permanent could create a different set of risks. The strongest market signal may come not from the oil rally itself, but from how producers and majors respond to it.
For traders, the energy sector now offers a clear contrast. $CNQ.TO and $COP have the most intuitive operating sensitivity to higher crude prices. $TRP.TO may attract attention as part of the Canadian energy complex, but the source data does not support assigning it a direct earnings uplift. Meanwhile, the retreat in Gulf bourses, depleted US oil stocks and renewed inflation pressure argue against treating the rally as a simple all-clear signal for equities.
Bull/Bear Verdict
Bull Case: Brent’s five-month high may support producer economics for $CNQ.TO and $COP, while constrained Strategic Petroleum Reserve stocks could keep supply concerns elevated.
Bear Case: The retreat in most Gulf bourses, the inflationary pressure from higher crude and uncertainty over oil-major spending could deepen risk aversion across US and Canadian equities.