A $900 million cost increase at one of the United States’ most closely watched lithium projects is not a minor budget adjustment. It is a warning that Washington’s critical-minerals ambitions may collide with the hard realities of construction, financing and execution.
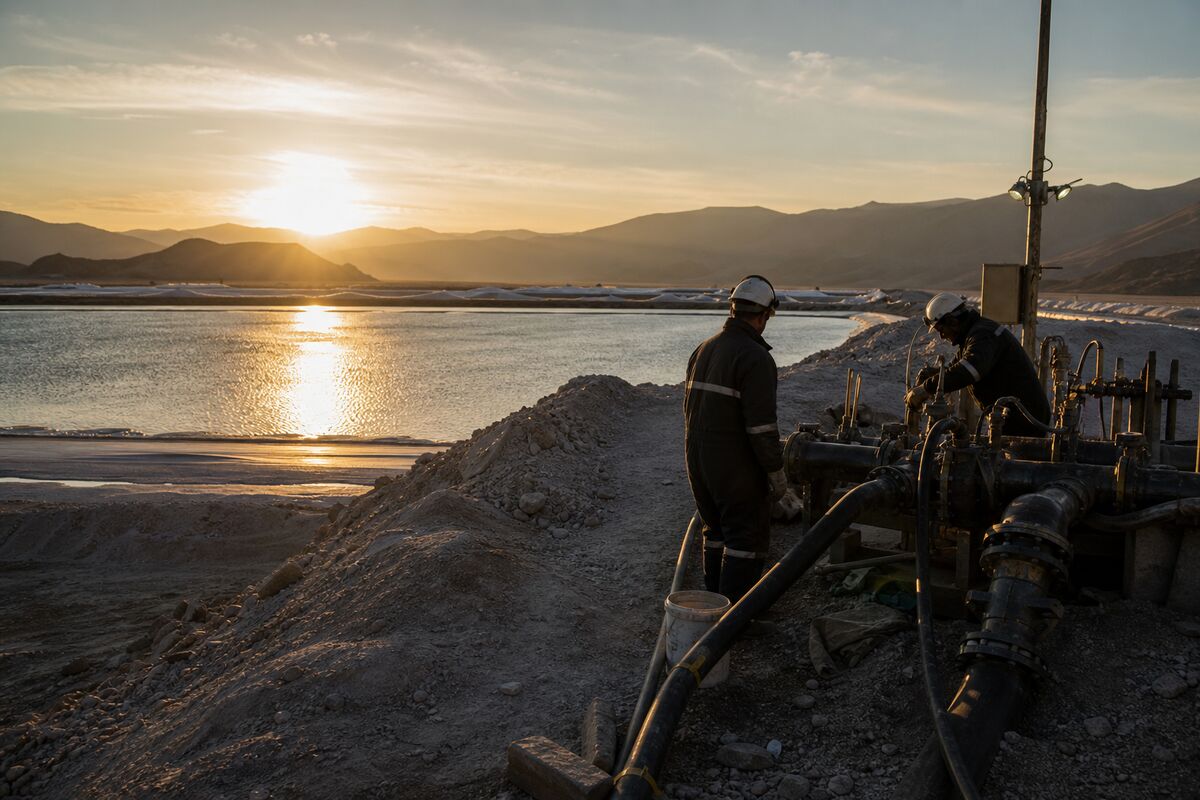
Lithium Americas has flagged the surge at Thacker Pass, its large lithium project in Nevada. The project is backed by the U.S. government, making the development more than a company-specific story. As Bloomberg reports, the cost escalation puts a sharper focus on the risks embedded in the broader push to build domestic sources of battery metals.
The policy case is clear. The project math is harder.
The United States wants more critical-minerals production at home, and large projects such as Thacker Pass sit at the center of that effort. Domestic supply could support the country’s battery and industrial objectives while reducing dependence on overseas sources. But policy urgency does not eliminate engineering complexity, labor constraints, procurement challenges or the need to keep a project funded through construction.
That distinction matters. Government backing may improve a project’s strategic importance and help attract capital, but it does not guarantee that the original cost assumptions will hold. A $900 million increase at Thacker Pass suggests that investors evaluating similar developments should look beyond announcements, permits and policy support. The more important question is whether a project can be delivered at a cost and pace that remain workable as conditions change.
Why one lithium project matters to the broader buildout
Thacker Pass is not the only project exposed to these pressures. Miners pursuing U.S. critical-minerals production may face comparable challenges as they move from development plans to physical construction. Projects can become more expensive when designs evolve, suppliers reprice work, schedules extend or execution proves more complicated than expected. The assignment here is not to declare that every project will suffer the same increase. It is to recognize that the risk is no longer theoretical.
For investors, cost overruns can affect a project through several channels. Higher construction costs may increase the amount of capital required before production begins. Delays can push back the point at which a project contributes to domestic supply. Additional funding needs may also complicate financing discussions, particularly when a project already depends on a long development timeline and uncertain operating conditions.
Those effects can reinforce one another. A larger budget may require more financing; additional financing may raise the threshold for commercial success; and a more demanding construction program may increase scrutiny from lenders, government agencies and shareholders. Even without a stock-price move or a new operating forecast, the Thacker Pass disclosure provides a useful test of how markets should assess government-backed mining projects.
The investor lesson: strategic does not mean simple
The critical-minerals theme remains strategically important, but strategic importance should not be confused with execution certainty. Policymakers may support domestic battery-metal supply, yet miners still have to build and operate projects in the real world. The Thacker Pass cost surge indicates that public support can coexist with material development risk.
That is the contrarian point. The market has spent years focusing on the need for more domestic supply. It may now need to focus more heavily on the cost of delivering that supply. A project can be important to national policy and still face escalating capital requirements. It can receive government backing and still encounter construction problems. Those are not contradictions; they are the central investment questions.
Thacker Pass therefore deserves attention not simply because Lithium Americas reported a $900 million increase, but because the disclosure may serve as a reference point for the entire U.S. critical-minerals buildout. Other miners may not experience the same outcome, but they could face similar scrutiny over budgets, schedules, funding and execution. Until those risks are better understood, the domestic supply story carries a meaningful—and very concrete—implementation challenge.
Bull/Bear Verdict
Bull Case: Thacker Pass remains a large, government-backed U.S. lithium project, and its development could support the broader goal of expanding domestic battery-metal supply if the cost increase can be managed.
Bear Case: The reported $900 million cost surge suggests that construction, financing and execution risks could weigh on Thacker Pass and may confront other miners pursuing U.S. critical-minerals production.