Uranium Energy Corp. delivered the kind of headline the uranium market rewards: shares rose 6% after its multi-mine ramp-up produced a realized uranium price of $93.13. Against a broader move, that performance stands out—not because one trading session settles the sector’s outlook, but because operating execution and pricing are beginning to command equal attention.
The comparison is telling. The Global X Uranium ETF, trading on the NYSE Arca under $URA, gained approximately 1%, while Oklo and NuScale Power also ticked higher in sympathy trading. UEC’s larger move suggests that investors were responding to company-specific evidence as well as the wider North American nuclear-equities rally.
Why the $93.13 figure matters
A realized uranium price is more useful than a broad spot-market narrative when assessing a producer’s commercial performance. It reflects the price achieved on uranium sales and therefore gives investors a clearer lens on contract economics than a headline about market enthusiasm alone.
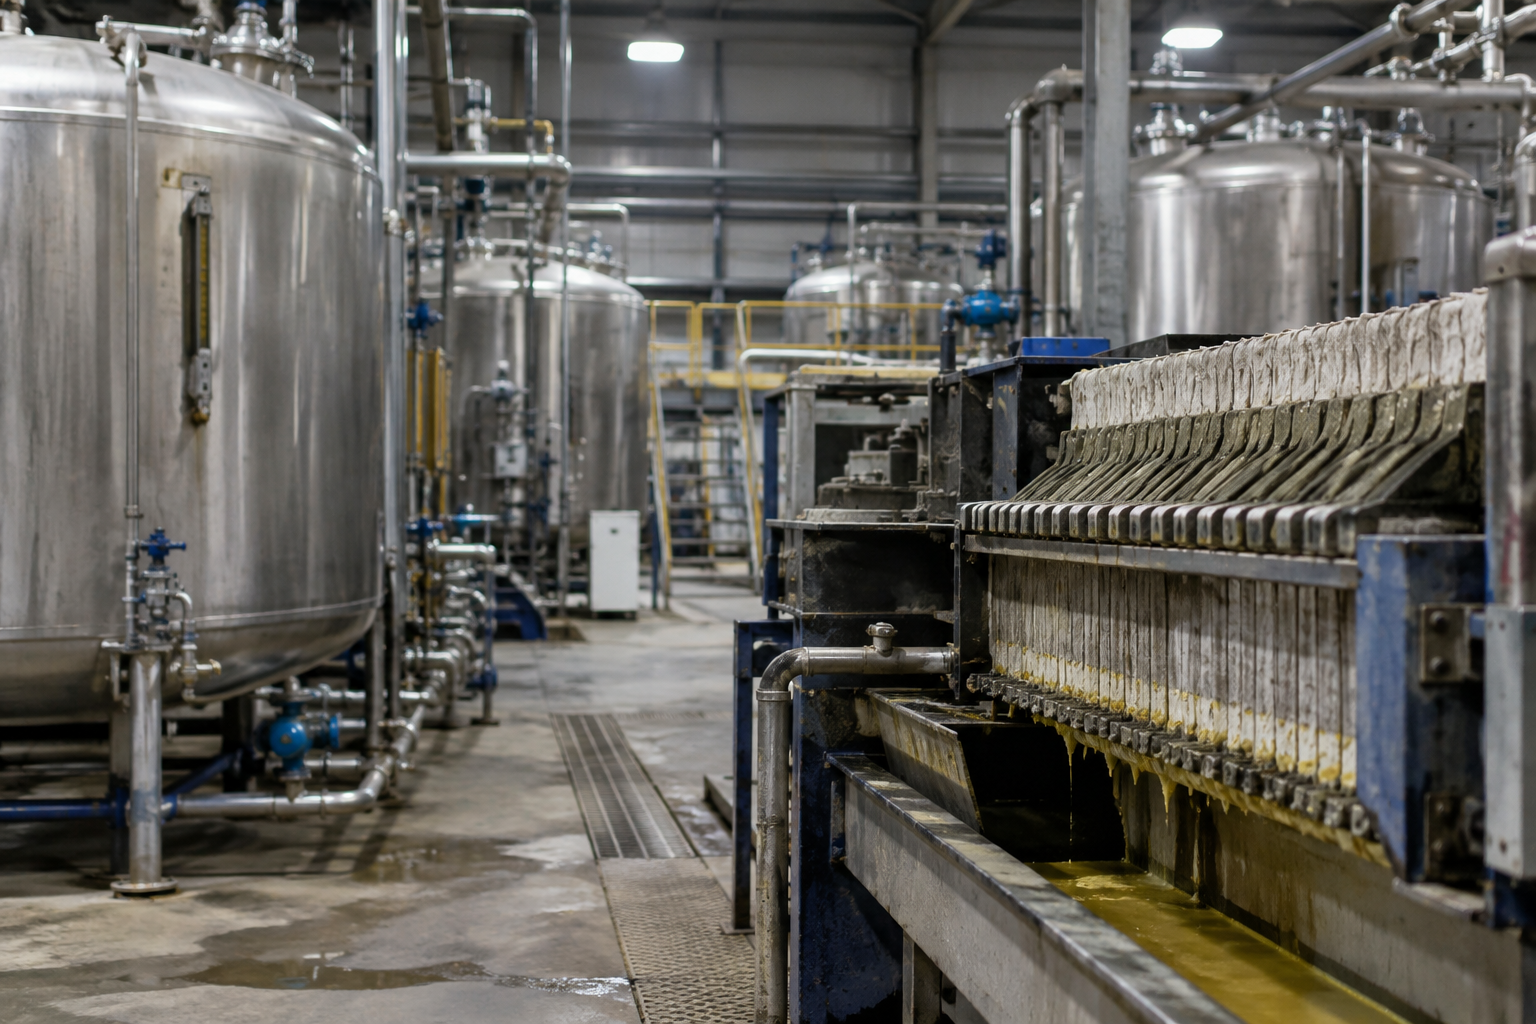
For UEC, the $93.13 figure arrives alongside a multi-mine ramp-up. That combination matters. Pricing tells the market what the company achieved on sales, while the ramp-up speaks to whether production is moving through an expanding operating platform. Together, the data may help investors assess potential operating momentum without relying solely on expectations about future uranium prices.
There is an important distinction, however. A realized price is not the same thing as a profit measure or a complete assessment of mine economics. The assignment provides no costs, margins, production volumes or cash-flow figures. The disciplined conclusion is narrower: UEC has reported a realized uranium price of $93.13 while ramping multiple mines, and that disclosure appears to have differentiated the stock from the broader ETF move.
Sector momentum is broad, but not uniform
The approximately 1% gain in $URA shows that the uranium theme was not confined to one company. Oklo and NuScale Power moved higher in sympathy trading, indicating that investors were also rotating attention toward companies associated with the nuclear-power buildout. Still, UEC’s 6% advance was materially larger than the ETF’s move, putting execution at the center of the session’s narrative.
In Canada, Cameco and NexGen Energy remain in focus as part of the continuing US and Canadian nuclear-equities discussion. Their presence matters because the North American fuel-supply story spans both established industry participants and companies tied to future uranium development. A market that rewards realized pricing and mine ramp-up data is likely to keep separating operating evidence from thematic enthusiasm.
Power demand keeps the fuel chain in focus
The broader significance extends beyond uranium producers. Utility demand and data-center power requirements are identified in the source material as important forces for nuclear fuel supply chains. If those demands continue to draw attention to nuclear generation, the market may increasingly scrutinize the availability, contracting and production of uranium needed to support that system.
That does not eliminate execution risk. Multi-mine ramp-ups must continue to translate into dependable operating performance, while realized prices need to be evaluated alongside volumes and costs—figures not provided here. The market’s reaction nevertheless makes the hierarchy clear: UEC’s reported $93.13 realized price gave investors a concrete operating datapoint, and the 6% share move reflected its relative impact.
For a closer look at the uranium and nuclear-equities backdrop, see the report on Uranium Energy’s 6% advance and realized pricing, along with this review of Cameco and other Canadian nuclear stocks.
Bull/Bear Verdict
Bull Case: UEC’s 6% gain, compared with approximately 1% for $URA, may indicate that the $93.13 realized uranium price and multi-mine ramp-up are giving the company stronger company-specific momentum within the North American nuclear-fuel rally.
Bear Case: The $93.13 realized price does not provide costs, margins or production volumes, so investors may still lack enough information to determine whether the reported ramp-up will translate into sustained operating performance.