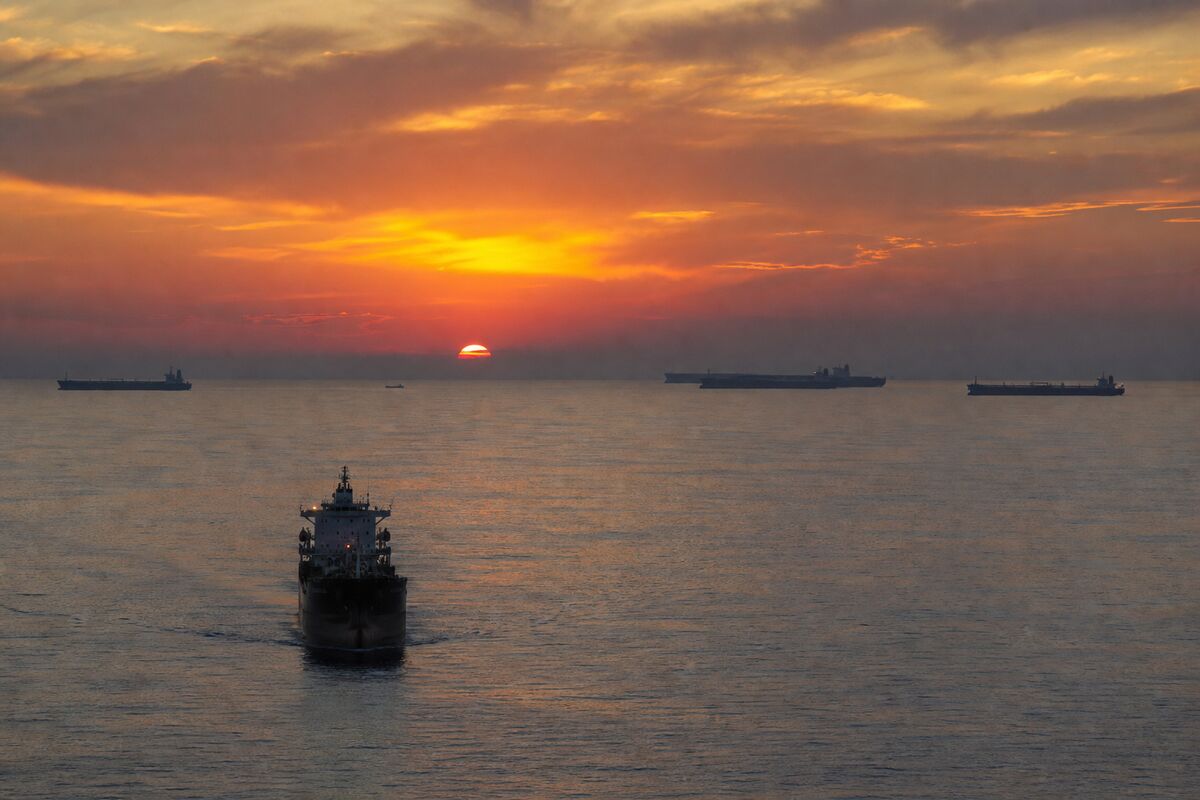
Oil is approaching a fourth consecutive monthly gain, but the market’s confidence comes with a geopolitical asterisk. A tanker attack near the Strait of Hormuz has brought supply risk back into the foreground, reminding traders that energy prices can be shaped as much by vulnerable shipping lanes as by barrels moving through pipelines and terminals.
That tension is now running through the US and Canadian energy markets. The threat of disruption may keep a premium embedded in WTI Crude and Brent Crude, while a 40-million-barrel loan from the US Strategic Petroleum Reserve offers a stabilizing counterweight. The result is a market caught between the fear of fewer barrels and the reality of emergency supply support.
The Strait of Hormuz remains one of the energy system’s most sensitive pressure points. A tanker attack in the area does not, by itself, establish a lasting interruption to global supply, but it highlights how quickly shipping security can become a pricing issue. For traders, the concern is not simply whether oil is physically unavailable today. It is whether producers, refiners and transport operators must pay more to navigate a market where the next disruption is difficult to time.
That uncertainty helps explain why the fourth-monthly-gain narrative matters. Without a specific price level in the source material, the signal is directional rather than numerical: oil-market strength has persisted across four consecutive months. WTI Crude and Brent Crude are the relevant gauges, and their performance may influence how investors assess the earnings environment for North American energy companies.
SPR barrels put a brake on the fear trade
The US loaned 40 million barrels from the Strategic Petroleum Reserve as the last share of a global agreement. That detail gives the market a second storyline alongside the Hormuz risk. Governments are not powerless observers when supply fears intensify; reserve barrels can offer additional supply and potentially soften the immediate impact of a disruption.
Still, an SPR release is not the same thing as a permanent solution. It may help stabilize expectations, but it does not remove the underlying security risk around a major energy corridor. The market tension is therefore straightforward: concerns about disrupted flows could support a geopolitical risk premium, while reserve activity could limit how far that premium travels.
For producers, including Exxon Mobil, sustained oil-price strength may improve the backdrop for upstream revenue, although the assignment provides no company-specific price move or operating result. Refiners face a more complicated equation. Higher crude costs can pressure input economics, while disruptions in transportation may affect the availability and regional pricing of feedstocks. Midstream companies sit between those forces, with their relevance tied to the movement and handling of energy rather than simply the headline price of crude.
LNG becomes insurance against a narrow chokepoint
QatarEnergy has reportedly purchased US and other LNG as a hedge against future disruptions around Hormuz. The move adds a gas-market dimension to an oil story. It suggests that energy buyers are thinking beyond the immediate cargo schedule and building flexibility into their supply arrangements.
That hedging could matter for US and Canadian LNG-linked businesses and infrastructure operators, though the available information does not identify any specific company or quantify the purchases. The broader message is more important than a single transaction: when a critical shipping route becomes less predictable, buyers may place greater value on diversified sourcing.
For North American energy equities, the backdrop is consequently neither a simple boom signal nor a clean warning. Sustained oil strength and geopolitical risk premiums could support the revenue environment for producers. At the same time, refiners may confront higher crude costs, while midstream operators remain exposed to questions about volumes, routes and logistics. LNG hedging may reinforce the strategic importance of US and Canadian supply, but it does not erase the operational complexity created by a fragile global transportation network.
The market’s next test is whether the Hormuz risk remains a temporary headline or becomes a persistent feature of energy pricing. The 40-million-barrel SPR loan may provide ballast, while QatarEnergy’s reported LNG purchases show how buyers are preparing for uncertainty. Until those forces resolve, WTI Crude and Brent Crude may continue to trade as barometers of both physical supply and geopolitical confidence. For more context on the developments, read the reported market coverage.
Bull/Bear Verdict
Bull Case: Oil being on track for a fourth consecutive monthly gain, combined with Hormuz-related supply risk and QatarEnergy’s reported LNG hedging, could support a durable geopolitical premium for North American energy producers and infrastructure.
Bear Case: The US loan of 40 million barrels from the Strategic Petroleum Reserve could help stabilize supply expectations, while higher crude costs and transportation uncertainty may complicate the outlook for refiners and midstream companies.