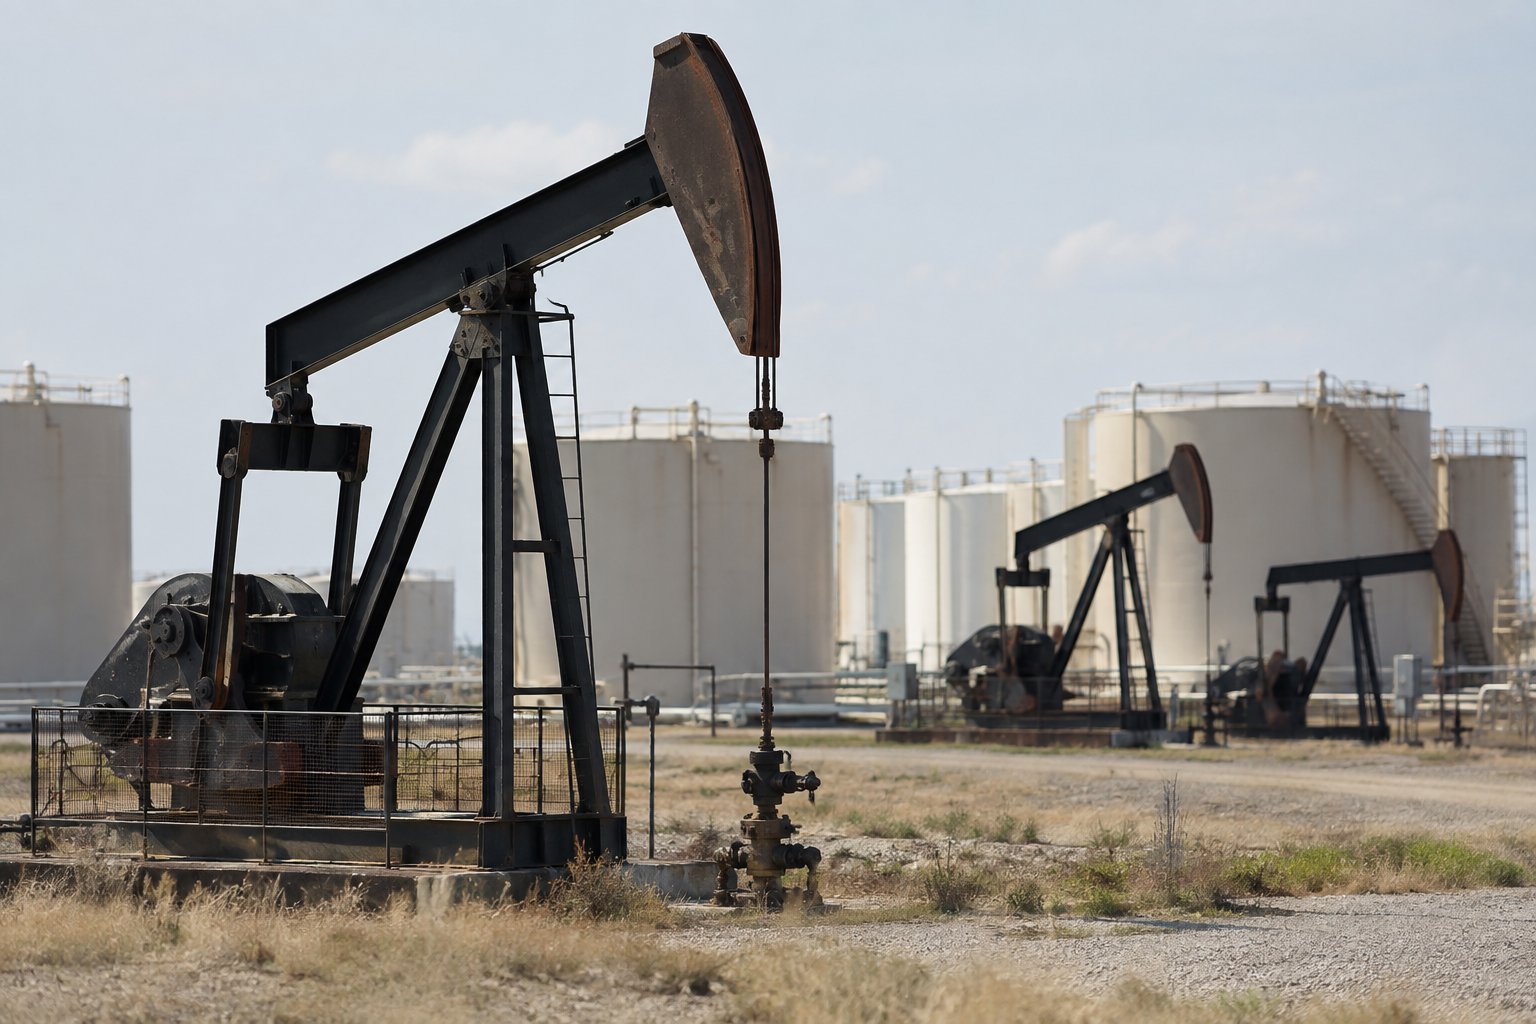
Oil’s nearly 3% decline is a reminder that crude prices can reprice quickly when geopolitical risk begins to fade. WTI crude was quoted near $93.05 per barrel and Brent crude near $105.54 as reports indicated that the United States and Iran were exploring a diplomatic path out of the war.
For North American markets, the move creates a sharp divide: lower crude prices could pressure producer revenue and equity valuations, while reducing energy costs for transportation, manufacturers and other oil-consuming industries. The key question is whether diplomacy can convert a single-session repricing into a sustained reduction in the risk premium embedded in crude.
Diplomacy Targets the Risk Premium
Reuters reported that oil prices dropped roughly 3% as US-Iran negotiations in New York moved into a more detailed technical phase. Separate reporting described the atmosphere as increasingly positive. That combination matters because crude had been carrying an additional geopolitical premium tied to the possibility of a prolonged conflict and potential disruption to supply.
A diplomatic breakthrough could reduce that premium even if physical production and consumption remain unchanged. In practical terms, traders may demand less compensation for holding crude exposure when the perceived probability of a wider disruption declines. The result could be downward pressure on benchmark prices such as WTI and Brent.
The Reuters-linked market report provides the central catalyst for the move. The price reference points remain clear: WTI near $93.05 and Brent near $105.54.
Energy Equities Face a Direct Test
Lower crude prices generally create a more difficult operating backdrop for oil producers because realized selling prices may decline. That pressure can flow through to revenue expectations, cash-flow estimates and valuation multiples, particularly for companies with greater sensitivity to oil prices.
Canadian oil sands producers could feel that pressure through weaker benchmark pricing and potentially narrower project economics. Suncor Energy and Canadian Natural Resources are therefore relevant names in the Canadian energy backdrop, even though the available data does not provide current share prices or valuation ratios for either company.
Canadian Natural Resources continues to attract investor attention because of its large dividend profile and steady cash generation. Those characteristics may offer a measure of appeal during commodity volatility, but they do not eliminate exposure to lower oil prices. For $CNQ, the market may weigh the durability of cash generation and the dividend profile against the possibility of weaker producer economics if crude prices continue to retreat.
Lower Oil Costs Broaden the Impact
The bearish read-through for producers is only one side of the market equation. Energy is an input cost across transportation, logistics, manufacturing and several other industries. A sustained decline in WTI and Brent could reduce fuel and feedstock expenses, potentially improving margins for oil-consuming businesses and easing cost pressure across the broader economy.
That creates a potential rotation in market leadership: crude-sensitive producers may face pressure while industries that consume substantial amounts of energy could receive a cost benefit. The magnitude would depend on whether lower prices persist and whether the decline reflects easing geopolitical risk rather than a sharp deterioration in economic demand.
Positioning Around an Unresolved Catalyst
The immediate message from the roughly 3% drop is that positioning built around conflict-related scarcity can unwind rapidly when negotiations show progress. Yet the technical phase of talks is not the same as a completed agreement. Until diplomacy produces durable, verifiable changes, crude may remain highly sensitive to headlines.
For North American energy investors, the data point is straightforward: WTI near $93.05 and Brent near $105.54 still represent elevated absolute prices, but the direction of the risk premium has shifted. Producers such as Suncor Energy and Canadian Natural Resources may face pressure if that premium continues to compress, while lower energy costs could support parts of the wider economy. The next move will depend less on a single diplomatic headline than on whether the increasingly positive atmosphere in New York becomes a durable path out of the conflict.
Bull/Bear Verdict
Bull Case: A sustained diplomatic breakthrough could reduce crude’s geopolitical risk premium, while WTI near $93.05 and Brent near $105.54 may still support cash generation and dividend attention for Canadian Natural Resources.
Bear Case: The roughly 3% oil decline could pressure producer revenues and valuations if negotiations continue to lower the risk premium, even as lower energy costs benefit oil-consuming industries.