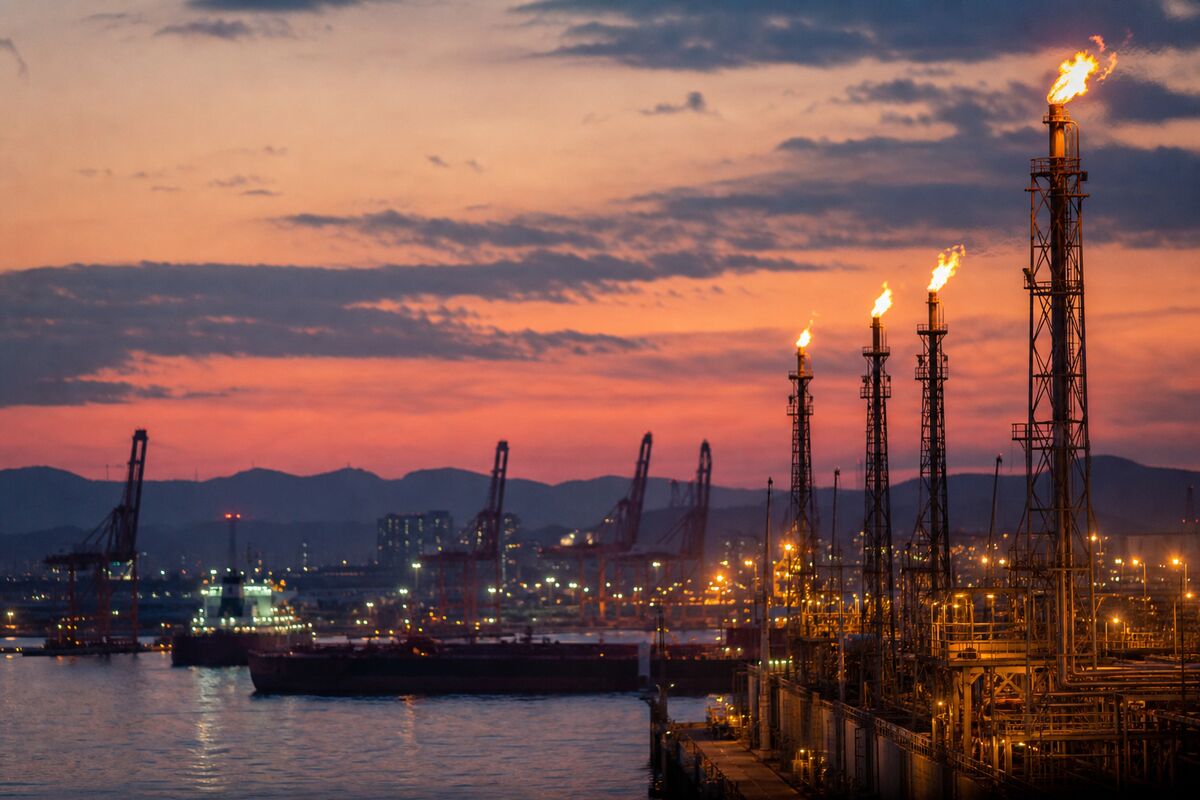
OPEC+ has chosen discipline over intervention, leaving December oil output targets unchanged while the Iran conflict keeps crude near six-month highs. That decision matters because the market is no longer trading only on barrels supplied; it is pricing the possibility that a strategic shipping chokepoint could become more dangerous.
WTI Crude and Brent Crude had already risen 2% earlier in the week and settled at six-month highs. With tanker fires and limpet mine attacks reported in the Strait of Hormuz, traders are assigning a geopolitical risk premium to oil. The next decisive variable may be whether talks in Doha produce de-escalation—or whether negotiations fail and supply fears deepen.
According to Reuters reporting, OPEC+ maintained its December output targets despite continuing disruption linked to the Iran war. That is a notable signal. The producer group is not rushing to add supply simply because prices have moved higher, suggesting that members view the current shock as geopolitical rather than a clear structural shortage requiring an immediate policy response.
Supply discipline meets geopolitical risk
The decision creates a two-sided market. On one side, unchanged targets reinforce supply discipline. If OPEC+ believes the disruption could ease, holding policy steady avoids an unnecessary shift in output guidance. On the other, the absence of additional barrels leaves crude more exposed to further incidents around the Strait of Hormuz.
That exposure is central to the outlook for Brent Crude, the global benchmark most directly connected to seaborne trade. WTI Crude may also reflect the same geopolitical premium, although the two benchmarks can respond differently to regional supply concerns and transportation disruptions. The assignment provides no basis for a specific price target, and traders should focus instead on the direction and durability of the risk premium.
Doha talks are the market's pressure valve
Iranian negotiators remain in Doha for talks aimed at ending the US-Iran war. Progress could change the market's supply-risk outlook quickly. A credible path toward de-escalation may reduce fears surrounding tanker traffic and weaken the premium attached to potential disruption. That would shift attention back toward OPEC+ policy and underlying demand conditions.
Failure, by contrast, could leave the market focused on escalation. Continued attacks, additional tanker incidents or a broader threat to shipping could make unchanged OPEC+ targets look less like a stabilizing policy and more like a constraint on available supply. The market does not need an actual loss of production to react; the possibility of delayed or disrupted shipments can be enough to keep crude elevated.
What it means for North American energy equities
US and Canadian producers may receive support from a sustained geopolitical premium in WTI Crude and Brent Crude, because higher benchmark prices can improve the revenue backdrop across the sector. But the benefit is not automatic. A conflict-driven price move can also increase uncertainty around transportation, operating costs and future demand.
For North American energy equities, the key question is whether crude strength proves durable or fades with diplomatic progress. A short-lived spike driven by Hormuz headlines would carry a different implication than a prolonged period of elevated prices supported by supply discipline. The distinction matters for investors assessing the sector without relying on company-specific performance data, which is not provided here.
Inflation expectations remain part of the trade
Oil's next move could also influence inflation expectations. If the conflict keeps shipping risks elevated and crude remains near six-month highs, energy costs may continue to complicate the inflation outlook. De-escalation could reverse part of that pressure by removing some of the geopolitical premium. Either way, the market is watching diplomatic headlines as closely as production quotas.
The bottom line is straightforward: OPEC+ has held the line, while geopolitics has set the price tone. Until the Doha talks clarify whether the conflict is widening or winding down, WTI Crude and Brent Crude may remain highly sensitive to every development around the Strait of Hormuz.
Bull/Bear Verdict
Bull Case: OPEC+'s unchanged December targets, the earlier 2% weekly rise and tanker-related disruption may keep a geopolitical premium embedded in WTI Crude and Brent Crude, potentially supporting the broader US and Canadian energy backdrop.
Bear Case: Progress in Doha could reduce supply-risk fears, unwind part of the premium behind the six-month highs and leave North American energy equities exposed to weaker crude pricing expectations.