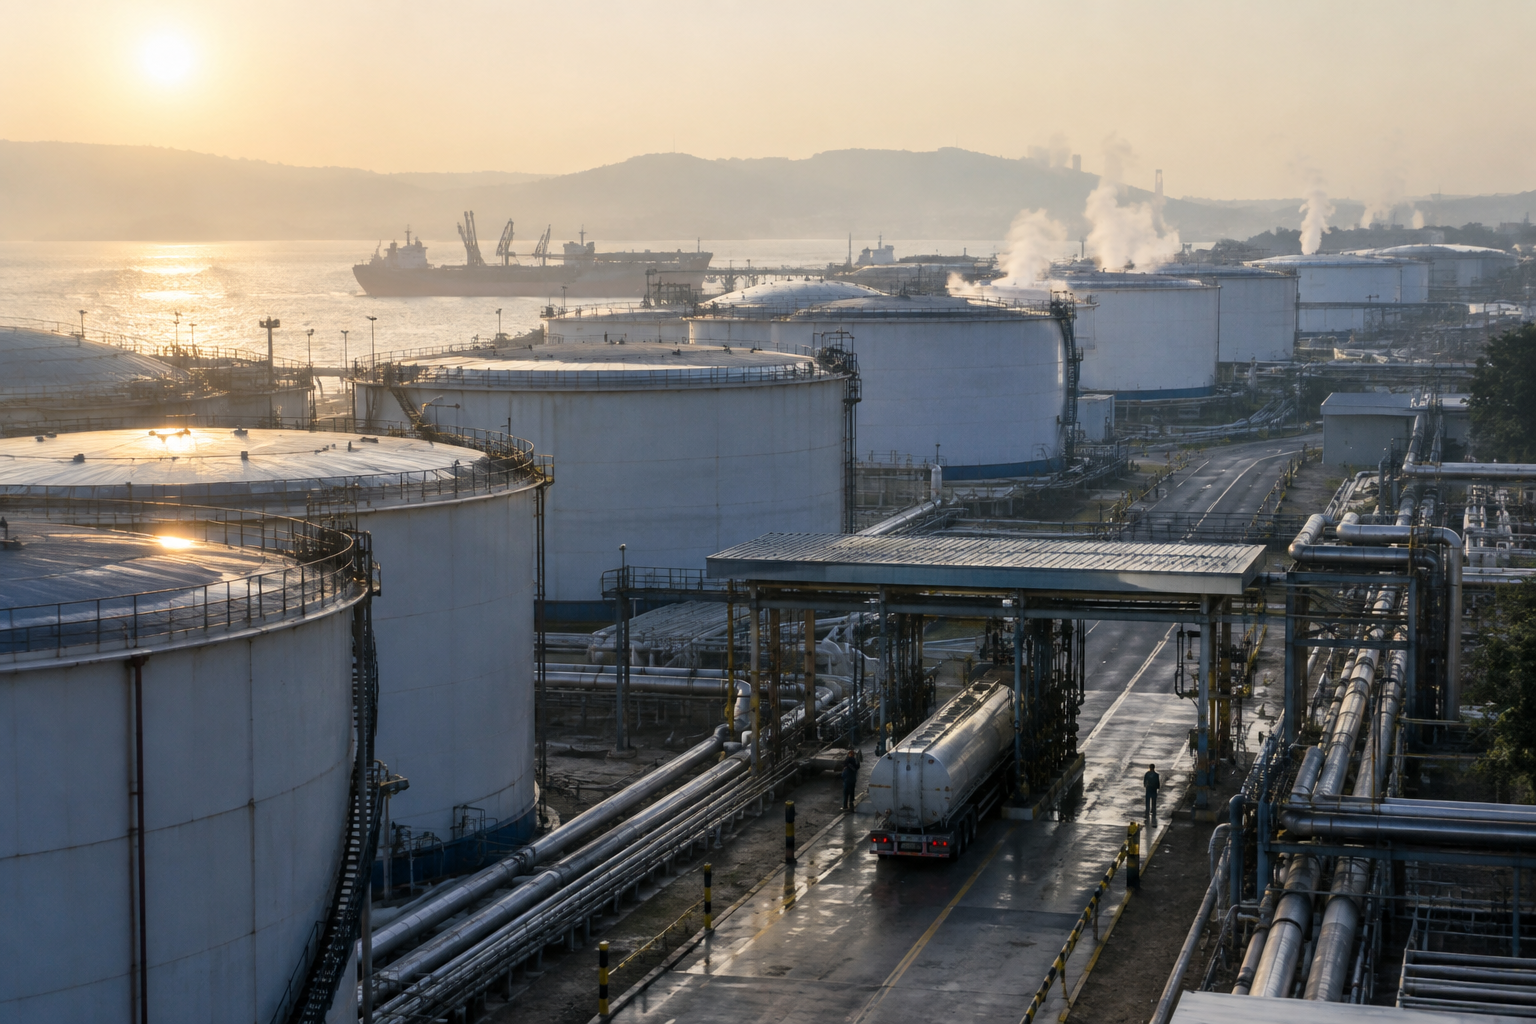
Oil markets are suddenly navigating a supply story with two opposing currents: possible coordinated releases of diesel and crude stocks on one side, and Iran-related disruptions to planned production expansion on the other. The result was a sharp repricing, with oil prices falling more than 2% as traders weighed whether government barrels could arrive before physical supply tightness becomes the dominant theme.
For energy equities, that tension matters. Lower crude prices can cloud the outlook for US and Canadian producers and refiners, yet company-specific balance-sheet progress can still cut against the broader commodity move. Occidental Petroleum, or $OXY, is the clearest case study: Goldman Sachs upgraded the stock to Buy while the oil market absorbed fresh pressure from potential reserve releases.
Diesel barrels become the market’s immediate question
According to the supplied Reuters context, Europe is weighing a new diesel-stocks release after pressure from the United States. That possibility has shifted the market’s focus from abstract geopolitical risk to the practical question of how quickly refined-product inventories could be put back into circulation.
A diesel release would not be identical to a crude release, but both would carry the same broad message: policymakers may be willing to lean against supply stress. For traders, the prospect of coordinated action can weigh on crude benchmarks before a single barrel is actually released. Expectations themselves become a tradable force, compressing the premium attached to disruption and potentially amplifying near-term volatility.
OPEC+ timing adds another layer
The supply picture is hardly straightforward. OPEC+ delayed its oil-capacity review after the Iran war disrupted expansion plans. That delay leaves market participants with less clarity about how much production capacity can be added, when it can be added and how the group’s longer-term supply framework may evolve.
In other words, the market is being asked to price a potential near-term supply cushion while also acknowledging that capacity plans have been knocked off schedule. That combination can produce abrupt swings: reserve releases may pressure prices now, while unresolved expansion delays keep a geopolitical and operational premium lurking underneath.
The implications extend across North American energy markets. Producers may face a less supportive crude-price backdrop if releases are coordinated and sustained. Refiners, meanwhile, are watching the diesel channel specifically, where additional stocks could alter product-market expectations. Neither outcome is certain, but the policy discussion alone may keep US and Canadian energy shares sensitive to every headline about inventories, capacity and regional supply disruptions.
Occidental’s company story versus the barrel
Occidental offers a useful reminder that an energy stock is not simply a leveraged expression of the oil price. Goldman Sachs upgraded Occidental Petroleum to Buy, citing the company’s debt reduction and cash-flow trajectory as part of the thesis supplied with the report.
That creates a direct tension for $OXY. A decline of more than 2% in oil prices can challenge the sector’s broad earnings narrative, particularly when investors are considering how reserve releases might affect crude benchmarks. Yet progress on debt reduction and cash flow may give Occidental a company-specific argument that does not rise and fall entirely with the day’s commodity tape.
The distinction is important for traders. A falling oil price can pressure the group’s macro multiple, while improving financial discipline may support a more constructive view of one issuer. Goldman’s upgrade does not erase commodity exposure, and the reserve-release debate does not erase Occidental’s balance-sheet narrative. Instead, the two forces now sit in the same trade: macro pressure against an individual corporate improvement story.
The market’s next test
The immediate test is whether discussions about diesel and crude-stock releases become a coordinated policy response or remain an expectations-driven headline risk. Until that becomes clearer, oil may continue to react sharply to changes in perceived supply rather than only to confirmed physical flows.
For US and Canadian energy producers and refiners, that means volatility may remain the central theme. The oil market has been handed a potential short-term cushion, an OPEC+ review delay and Iran-related supply uncertainty all at once. Occidental’s Goldman-backed debt-reduction and cash-flow case stands apart—but it must still be assessed against the price of the barrel.
Bull/Bear Verdict
Bull Case: Goldman Sachs’ Buy upgrade, together with Occidental’s debt reduction and cash-flow trajectory, may support a more constructive company-specific view even as oil prices fall more than 2%.
Bear Case: Coordinated diesel and crude-stock releases could pressure crude benchmarks and near-term volatility, while the delayed OPEC+ capacity review and Iran-related disruptions leave the broader energy outlook unusually unsettled.