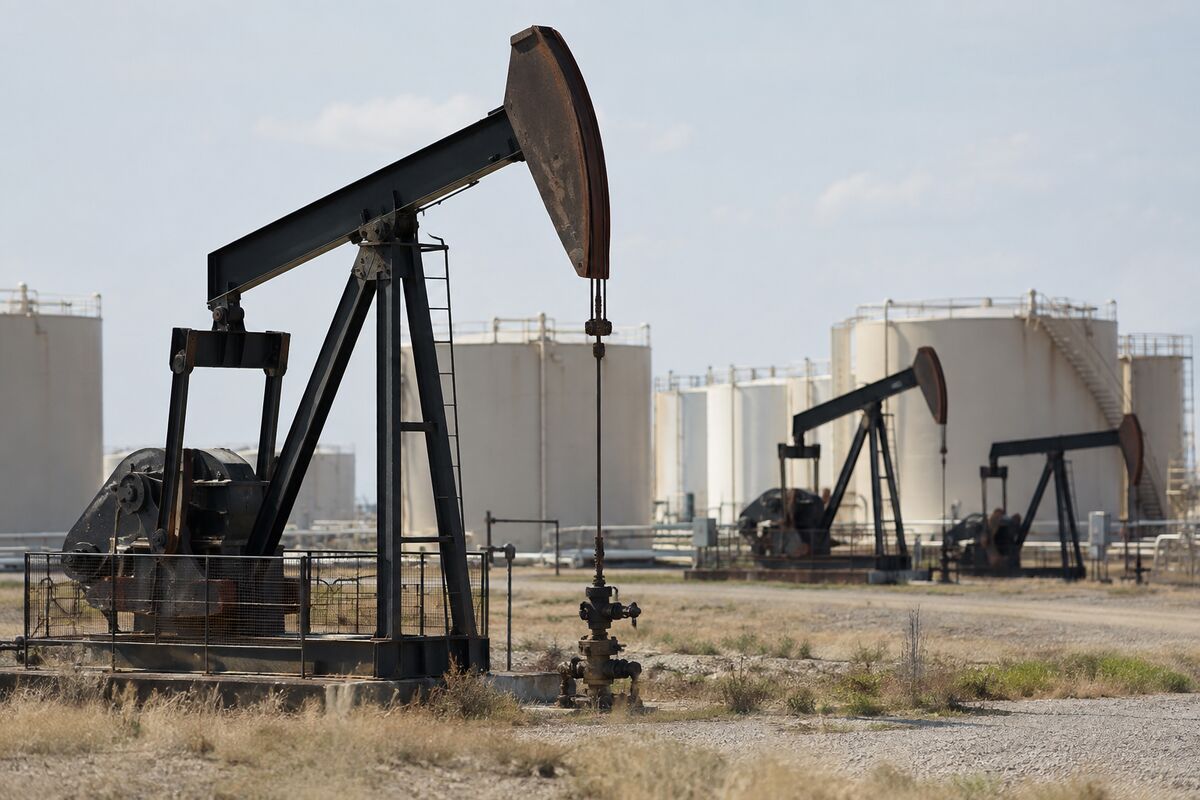
Oil’s geopolitical premium is unwinding fast—and energy equities are paying the bill. Crude fell about 6% on hopes for a U.S.-Iran deal, while U.S. stock-index futures jumped, according to Reuters’ report.
The market is making a blunt statement: if diplomacy can reduce the probability of a major Iran-related supply disruption, the war-risk premium embedded in crude may be worth considerably less. That repricing is constructive for the broader equity tape, but it creates an immediate headwind for producers whose earnings expectations are sensitive to oil prices.
Crude’s reversal is the central signal
Investing.com data showed crude down 4.0% from a 52-week high of $117.63 to a session close near $99.96. The move matters beyond the headline percentage. Oil had been carrying a premium tied to the possibility that tensions involving Iran could threaten supply. Hopes for a U.S.-Iran agreement are now prompting traders to reduce that exposure.
This is the classic distinction between a supply shock and a risk premium. If barrels are not physically removed from the market, prices can still rise when traders assign a greater probability to disruption. When that probability declines, the premium can unwind quickly. Today’s action suggests the market is pricing a lower chance of a major Iran-related interruption, at least for now.
That does not eliminate uncertainty. It does, however, change the near-term trading framework. The question is no longer simply how much oil might be lost; it is how much geopolitical insurance was already reflected in crude near its 52-week high.
U.S. producers face a tougher tape
For U.S. producers such as OXY and DVN, a lower oil-price environment could pressure the revenue assumptions that supported recent energy positioning. The assignment provides no stock-price data for either company, so the conclusion must remain measured: falling crude may weigh on sentiment toward producers, particularly if traders believe the geopolitical premium will continue to fade.
At the same time, stronger U.S. stock-index futures show that the market is not treating lower oil as an across-the-board negative. For consumers and oil-sensitive parts of the economy, cheaper crude may be viewed as a relief. That rotation can benefit broader equity-market positioning even as it challenges energy exposure.
Canadian energy stocks feel the pressure
Canadian energy stocks moved lower alongside crude. Cenovus Energy declined 3.65%, while Cardinal Energy fell 3.85%. Those moves underline the sector’s sensitivity to a rapid change in the oil narrative: when traders remove war-risk premium, producers can face pressure even if the underlying companies have not reported a new operational event.
The broader market backdrop was more constructive. The FTSE 100 recorded a fourth straight day of gains as oil prices declined on deal hopes. For U.S. and Canadian investors, that contrast is instructive. Lower crude can hurt energy stocks while supporting a wider risk-on tone, forcing traders to distinguish between sector weakness and broader equity strength.
The positioning question
The immediate issue is whether this is a temporary headline-driven adjustment or the beginning of a deeper normalization in crude pricing. If U.S.-Iran deal hopes hold, the premium may continue to compress. If negotiations falter, some of that premium could return.
For now, the data point in one direction: crude near $99.96, down 4.0% from its $117.63 52-week high, U.S. futures higher, and Canadian energy stocks under pressure. The market is rewarding reduced geopolitical stress while reassessing the value of energy exposure.
Bull/Bear Verdict
Bull Case: Hopes for a U.S.-Iran deal could continue reducing the war-risk premium, supporting broader equities as U.S. stock-index futures rise and crude retreats from $117.63 toward $99.96.
Bear Case: A sustained decline in crude could keep pressure on energy producers, with Cenovus Energy down 3.65%, Cardinal Energy down 3.85%, and U.S. names such as OXY and DVN exposed to weaker oil sentiment.